Credit Score Needed for Mortgage Approval: 2026 Guide
The credit score needed for mortgage approval varies by loan type. Learn the minimums, how scores affect rates, and how to improve yours before applying.
By Landon Hayes
Your credit score is the single most important number in your mortgage application. It influences whether you get approved, what interest rate you receive, and how much you will pay over the life of the loan. A difference of just 20 points can mean tens of thousands of dollars in extra interest. Understanding the credit score needed for mortgage approval helps you plan ahead, fix problems early, and approach lenders with confidence.
MortgageZone is an educational platform that connects you with a network of lenders. We are not a lender ourselves, but we help you compare quotes and find the right loan for your situation. This guide explains the credit requirements for different loan types, how lenders evaluate your profile, and practical steps to improve your score before you apply.
What Credit Score Do You Need for a Mortgage?
There is no single answer to this question because minimum credit score requirements vary by loan program and lender. Government-backed loans tend to have lower thresholds, while conventional loans typically require higher scores. Lenders also consider your entire financial picture, including income, debt-to-income ratio, and down payment.
Here are the general minimum credit score requirements for major mortgage types:
- Conventional loans: 620 minimum, though many lenders prefer 740 or higher for the best rates
- FHA loans: 580 with a 3.5% down payment, or 500 with a 10% down payment
- VA loans: No official minimum, but most lenders look for 620 or higher
- USDA loans: 640 for automated approval, though some lenders accept lower with manual underwriting
- Jumbo loans: 700 or higher, with some lenders requiring 720 or more
These are baseline numbers. Meeting the minimum does not guarantee approval, and falling slightly below does not automatically disqualify you. Lenders weigh your credit score alongside other factors, and some may make exceptions for strong compensating factors like large cash reserves or a long employment history.
How Lenders Evaluate Your Credit
Your credit score is just one piece of the puzzle. Lenders use a process called underwriting to assess whether you are likely to repay the loan. They review your credit report, verify your income and employment, and calculate your debt-to-income ratio (DTI). Understanding how these elements work together helps you anticipate what lenders look for.
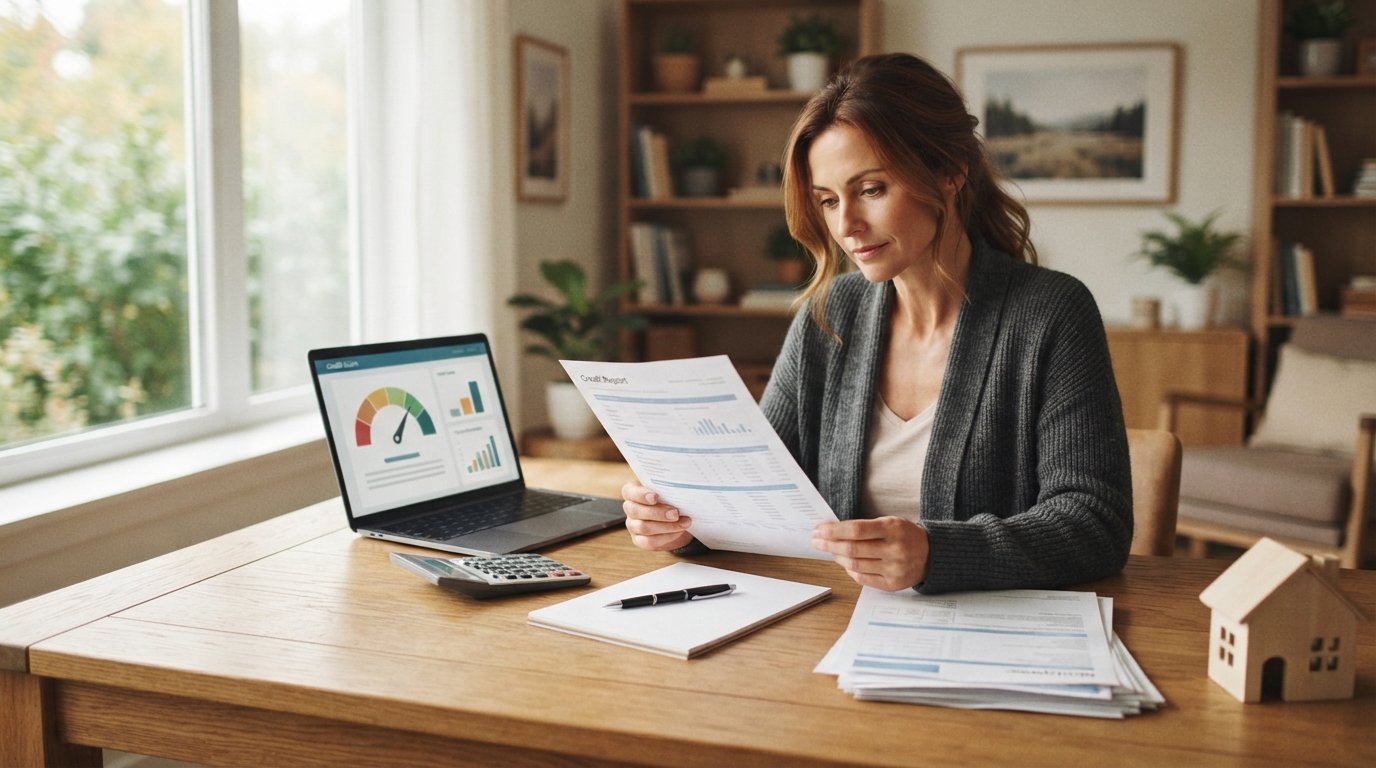
Your credit report contains detailed information about your payment history, outstanding balances, credit utilization, and the age of your accounts. Lenders look for patterns of responsible borrowing. Late payments, collections, bankruptcies, and foreclosures raise red flags. On the other hand, a long history of on-time payments and low balances signals reliability.
Debt-to-income ratio measures how much of your monthly income goes toward debt payments. Most lenders prefer a DTI below 43%, though some loan programs allow higher ratios with compensating factors. If your credit score is on the lower end, a strong DTI and a larger down payment can improve your chances of approval. If you want to understand how long the entire process takes, from application to closing, our guide on mortgage approval timeline steps and timeframes walks through each stage.
Why Your Credit Score Matters Beyond Approval
Your credit score does more than determine whether you qualify. It directly affects the interest rate you receive, which in turn impacts your monthly payment and the total cost of your loan. A higher score unlocks lower rates and better terms, saving you money every month for years.
Consider this example: On a $300,000 mortgage with a 30-year term, a borrower with a 760 credit score might qualify for a 6.5% interest rate, resulting in a monthly principal and interest payment of about $1,896. A borrower with a 640 score might receive a 7.5% rate, pushing the monthly payment to approximately $2,098. That is a difference of over $200 per month, or more than $72,000 over the life of the loan.
Beyond the interest rate, your credit score can influence your mortgage insurance premiums. FHA loans require mortgage insurance regardless of your score, but conventional loans with less than 20% down may have private mortgage insurance (PMI) that varies based on creditworthiness. A higher score can reduce or eliminate these costs sooner.
Credit Score Ranges and What They Mean for Your Mortgage
Credit scores fall into distinct ranges, each with different implications for mortgage shopping. Knowing where you stand helps you set realistic expectations and identify areas for improvement.
Here is a breakdown of credit score tiers and their typical mortgage outcomes:
- 760 to 850 (Excellent): Best available rates, widest range of loan options, easiest approval process
- 700 to 759 (Good): Competitive rates, most loan programs available, minor rate adjustments
- 650 to 699 (Fair): Higher rates, some loan restrictions, may need larger down payment
- 580 to 649 (Poor): Limited options, FHA loans may be the best path, higher costs
- Below 580 (Very Poor): Few conventional options, FHA with 10% down possible, focus on credit repair first
Moving from one tier to the next can significantly improve your mortgage terms. Even a modest increase of 20 to 30 points can open doors to better rates and loan programs. If you are close to a threshold, consider delaying your application to boost your score first.
Strategies to Improve Your Credit Score Before Applying
If your credit score is not where you want it to be, you have options. With time and deliberate effort, you can raise your score and improve your mortgage prospects. The key is to start early, ideally six to twelve months before you plan to apply.
Here are practical steps to boost your credit score:
- Check your credit reports for errors. Request free reports from all three major bureaus and dispute any inaccuracies. Errors are more common than you might think and can drag down your score.
- Pay down revolving balances. Credit utilization accounts for about 30% of your score. Aim to keep balances below 30% of your credit limits, and ideally below 10%.
- Make all payments on time. Payment history is the largest factor in your score. Set up automatic payments or reminders to avoid missed due dates.
- Avoid opening new credit accounts. Each new application generates a hard inquiry, which can temporarily lower your score. Keep new credit applications to a minimum before applying for a mortgage.
- Keep old accounts open. The length of your credit history matters. Closing old accounts can shorten your average account age and reduce your available credit.
These strategies take time to show results. Most credit improvements appear within one to two billing cycles, but significant score gains may take several months. Be patient and consistent, and avoid making large purchases or taking on new debt during this period.
When to Apply With a Lower Credit Score
Sometimes waiting is not an option. If you need to buy a home soon or refinance to reduce payments, you may need to apply with a lower credit score. In these situations, focus on loan programs designed for borrowers with less-than-perfect credit.
FHA loans are often the best choice for lower credit scores. They allow scores as low as 580 with a 3.5% down payment and have more flexible underwriting guidelines than conventional loans. VA loans, available to veterans and active-duty service members, have no official credit minimum and offer competitive rates. USDA loans support rural homebuyers with scores starting around 640.
If your score is below the minimum for these programs, consider working with a credit counselor or exploring down payment assistance programs. Some lenders offer portfolio loans with alternative underwriting standards, though these often come with higher rates and fees. At ExpressMortgageQuotes, you can explore mortgage options and compare quotes from multiple lenders to find the best fit for your financial situation.
How Different Loan Types Compare on Credit Requirements
Each mortgage program has its own credit score thresholds and underwriting standards. Understanding these differences helps you target the right loan for your profile and avoid wasted applications.
Conventional loans, backed by Fannie Mae and Freddie Mac, typically require a 620 minimum. However, lenders often impose higher overlays, meaning you may need a 640 or 660 to qualify with some institutions. The best rates go to borrowers with scores of 740 or above. Conventional loans offer the most flexibility in terms of property types and loan amounts.
FHA loans are more forgiving. With a 580 score and 3.5% down, you can qualify for a loan up to the FHA limit for your area. If your score is between 500 and 579, you may still qualify with a 10% down payment. FHA loans require mortgage insurance, but they are a solid option for first-time buyers and those rebuilding credit.
VA loans stand out for their flexibility. The Department of Veterans Affairs does not set a minimum credit score, but lenders typically require 620 or higher. VA loans offer no down payment, no monthly mortgage insurance, and competitive rates. They are available to eligible veterans, active-duty service members, and surviving spouses.
Planning Your Mortgage Application Timeline
Timing matters when you are working to improve your credit score. Rushing the process can lead to higher costs or denial. A thoughtful approach gives you time to address credit issues and position yourself for the best possible terms.
Start by pulling your credit reports and identifying any problems. If you find errors, dispute them immediately. If your balances are high, focus on paying them down. If you have late payments, make sure all future payments are on time. These steps take time, so begin at least six months before you plan to apply.
Once your credit is in good shape, gather your documentation: pay stubs, tax returns, bank statements, and proof of employment. Get preapproved before you start house hunting. Preapproval tells sellers you are a serious buyer and gives you a clear budget. It also locks in your rate for a set period, protecting you from market fluctuations.
Remember that your credit score is not the only factor. Lenders also look at your income stability, savings, and debt load. A strong overall financial profile can compensate for a less-than-perfect credit score. Work on all aspects of your finances to maximize your chances of approval.
Understanding the credit score needed for mortgage approval is the first step toward homeownership. Whether you are buying your first home, refinancing an existing loan, or exploring reverse mortgage options, your credit score shapes your opportunities. Take time to assess your credit, improve where you can, and compare offers from multiple lenders before committing. With preparation and the right approach, you can secure a mortgage that fits your budget and your goals.