Documents Needed for Online Mortgage Application: 2026 Checklist
Use this documents needed for online mortgage application checklist to organize income, identity, and asset files before you apply, so you avoid delays and multiple submissions.
By Valerie Owens
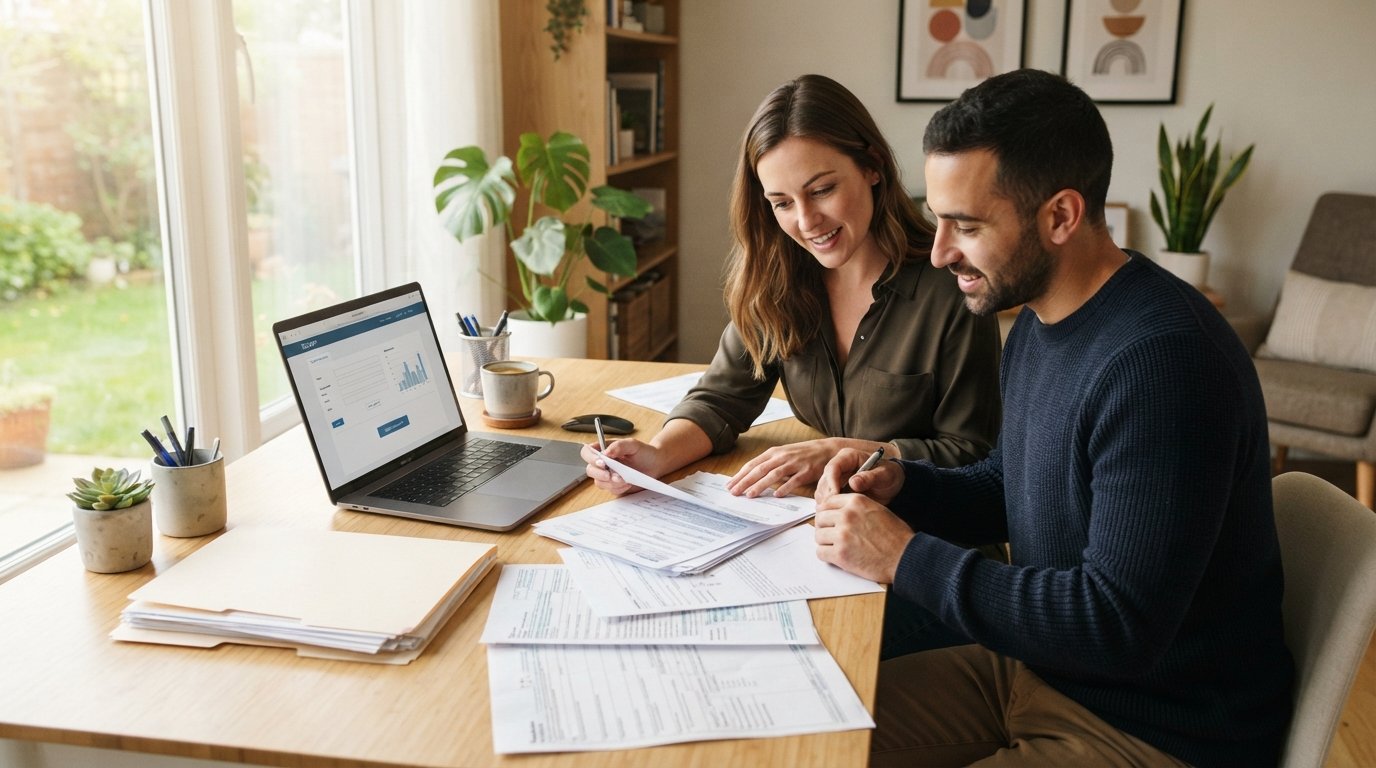
You are ready to buy a home, you have found a lender, and you are about to click the apply button on a digital mortgage portal. Then you see the upload page: tax returns, pay stubs, bank statements, and a dozen other fields. The documents needed for online mortgage application checklist can feel like a second job. The good news is that preparing the right paperwork before you start can turn a stressful, stop-and-go process into a smooth, single submission. Lenders are not trying to trip you up; they are verifying that you can repay what you borrow. In 2026, most of that verification happens through secure online portals, which means your job is to have clear, consistent, and complete digital files ready to go.
This guide walks you through the exact documents most online lenders request, how to scan and organize them securely, the mistakes that stall applications, and the special items self-employed and gig workers need. You will also see how to use MortgageZone's pre-application checklist before you request quotes from participating Network Members. Getting this right the first time saves days of back-and-forth and helps you compare offers with confidence.
Core Income and Identity Documents Most Online Lenders Request
Online mortgage applications in 2026 still rely on the same foundational documents that paper applications did, but the delivery method has changed. Lenders want to confirm who you are, how much you earn, how stable that income is, and whether you have the funds to close. Most portals will ask for these items in a specific sequence, and missing one can pause your application until it is resolved. The list below covers the documents needed for online mortgage application checklist for the majority of W-2 employees and salaried borrowers.
- Government-issued photo ID: A driver's license, state ID, or passport. Make sure the image is clear and the expiration date is visible.
- Social Security number verification: Usually entered directly into the portal, but some lenders ask for a copy of your Social Security card or a W-2 that shows the number.
- Recent pay stubs: Typically the last 30 days, covering at least two pay cycles. If you are paid biweekly, that means two stubs; if weekly, four.
- W-2 forms: The last two years of W-2s from each employer. If you changed jobs, provide W-2s from all employers in that period.
- Federal tax returns: The last two years of personal returns, including all schedules and attachments. If you are self-employed, this is non-negotiable.
- Bank statements: The last two to three months for all accounts you plan to use for the down payment and closing costs. Lenders want to see seasoned funds, not money that just appeared.
- Retirement and investment statements: The most recent quarterly or monthly statements for 401(k)s, IRAs, brokerage accounts, and any other asset you plan to use.
- Gift letters: If a family member is helping with the down payment, you will need a signed gift letter stating the amount and that repayment is not required, plus documentation showing the transfer.
- Rental history: Some lenders ask for landlord contact information or cancelled rent checks for the past 12 months, especially for first-time buyers without a long credit history.
These items form the backbone of your file. The exact combination depends on your loan type and employment situation, but having them ready in digital form will cover the first round of requests from almost any online lender. For a deeper walkthrough of the digital application flow itself, see our guide on how to submit a mortgage application online, which pairs well with this checklist.
How to Scan, Upload, and Organize Documents Securely
Once you know what to gather, the next step is preparing your files for the portal. A blurry photo of a tax return or a bank statement saved as a .png when the portal only accepts .pdf can delay your application by days. Lenders use secure upload systems, but they still need legible, complete documents. The goal is to make your file easy to review and easy to audit. A few simple habits make a big difference.
Start by using a dedicated scanner app on your phone or a flatbed scanner if you have one. Scanning apps automatically detect edges, adjust brightness, and save as PDF, which is the preferred format for most mortgage portals. Avoid taking a quick photo with your camera roll unless the app has a document mode; shadows and angles are common reasons a processor asks you to resubmit. Name each file clearly, such as "2025_W2_EmployerName.pdf" or "Chase_Checking_Jan2026.pdf". This naming convention helps you and the processor find documents quickly if questions arise.
Security matters too. Only upload documents through the lender's encrypted portal, never by email. If a lender asks for documents by email, confirm that their system is secure or use their portal's secure message feature. Keep a master folder on your computer or cloud storage with subfolders for identity, income, assets, and debts. This master folder becomes your single source of truth if you apply with more than one lender through MortgageZone's quote comparison process. When you request quotes from Network Members, you can reuse the same organized files, which speeds up each application.
Common Document Mistakes That Stall an Online Mortgage Application
Even borrowers with strong finances can hit delays because of small documentation errors. Underwriters are trained to spot inconsistencies, and an online portal flags missing or mismatched items automatically. The most common mistakes are not about fraud or bad credit; they are about completeness and consistency. Here are the pitfalls to avoid.
- Missing pages: Tax returns without all schedules or bank statements with a page cut off are treated as incomplete. Always scan the entire document, including blank pages that are part of the official form.
- Unseasoned funds: A large deposit that appeared two weeks before applying will raise questions. Be ready to source any deposit that is not a regular paycheck or transfer between your own accounts.
- Name inconsistencies: If your ID says "Robert" but your pay stubs say "Bob," provide a letter explaining the difference or use documents that match your legal name.
- Expired documents: An expired driver's license or a tax return that is more than two years old will be rejected. Check expiration dates before uploading.
- Illegible scans: Faded text, cut-off numbers, or skewed images cause processors to request resubmission. Review each file before uploading.
Another frequent issue is uploading documents for the wrong loan program. For example, FHA loans have specific requirements for gift funds and FHA case numbers, while VA loans require a Certificate of Eligibility. If you are comparing loan types, tell your lender which program you are considering so they can send the correct checklist. MortgageZone's platform connects you with lenders who specialize in different programs, and each Network Member will provide a tailored document list based on your scenario.
What Self-Employed and Gig-Economy Borrowers Should Prepare
If you earn income from freelancing, consulting, rideshare driving, or an LLC, your documentation burden is heavier. Lenders need to see that your income is stable and likely to continue, which is harder to prove without a traditional employer. The documents needed for online mortgage application checklist for self-employed borrowers go beyond W-2s and pay stubs. Expect to provide the following.
- Two years of personal tax returns: All schedules, including Schedule C, Schedule E, and K-1s if you have partnerships or S-corporations.
- Two years of business tax returns: If you file separately for your business, provide the full business returns with all statements and schedules.
- Year-to-date profit and loss statement: A current P&L prepared by you or your accountant, showing income and expenses for the current year.
- Business bank statements: The last three to six months, depending on the lender, to verify business revenue and expenses.
- 1099 forms: For gig workers and independent contractors, the last two years of 1099-NEC or 1099-MISC forms.
- Client contracts or letters of intent: Some lenders ask for proof of ongoing work, especially if your income varies significantly from year to year.
Gig-economy borrowers should also be ready to explain deductions. A common mistake is claiming large business expenses that reduce your taxable income, which also reduces the income the lender can count. If your reported income is low because of deductions, consider working with a lender who specializes in self-employed borrowers and understands how to calculate qualifying income. MortgageZone's Network Members include lenders experienced with non-QM and self-employed files, so you can compare options that fit your situation. For broader mortgage education and tools, resources like RefinancingCo offer calculators and guides that complement your application preparation.
Using MortgageZone's Pre-Application Checklist Before Requesting Quotes
Before you start comparing offers, take advantage of MortgageZone's pre-application checklist. The platform is designed to simplify the mortgage process by connecting you with participating lenders, and a little preparation on your end makes the quote comparison more accurate. The pre-application checklist helps you organize your documents, understand what each lender will ask for, and avoid the multiple submissions that slow down the process.
Here is how to use it effectively. First, gather the core documents listed earlier and save them in a dedicated folder. Second, review your credit report for errors, since lenders will pull your credit and discrepancies can stall an application. Third, use MortgageZone's mortgage calculator to estimate your monthly payments and understand how different loan amounts and rates affect your budget. Fourth, fill out the pre-application checklist with your income, assets, and debts so you have consistent numbers ready when you request quotes. Fifth, when you are ready, request quotes from Network Members through the platform. Because you have your documents organized, you can respond quickly to each lender's requests and compare offers side by side.
MortgageZone is not a lender, mortgage broker, or bank; it is a platform where you can request personalized quotes from Network Members. That means the documents you upload go directly to the lenders you choose, and each lender will have its own portal and requirements. The pre-application checklist is your roadmap, not a substitute for the lender's specific requests. Use it to prepare, then follow each lender's instructions carefully. This approach reduces the chance of missing a document and helps you get to a clear comparison of rates and terms faster.
Finally, keep your document folder updated as your application progresses. Pay stubs change every pay period, bank statements arrive monthly, and tax returns are updated annually. If your application takes several weeks, a lender may ask for the most recent statement or pay stub to keep your file current. Staying organized from the start makes those updates quick and painless. With the right documents ready and a clear checklist in hand, you can move through the online mortgage application with confidence and focus on the exciting part: choosing the home and the loan that fit your life.