Fixed vs Adjustable Rate Mortgage: Which Is Better?
Fixed vs adjustable rate mortgage: which is better for your budget? Compare payment stability, initial savings, and long-term risk to choose the right loan.
By Author 1
Choosing between a fixed rate and an adjustable rate mortgage is one of the most consequential decisions you will make as a homebuyer. The right answer depends entirely on your financial situation, how long you plan to stay in the home, and your tolerance for uncertainty. In this guide, we break down both loan types, compare their pros and cons, and help you determine which option aligns with your goals.
Fixed Rate Mortgages: Predictable Payments for the Long Haul
A fixed rate mortgage locks in your interest rate for the entire life of the loan, typically 15 or 30 years. That means your principal and interest payment stays the same every month, regardless of what happens in the broader economy. This predictability is the primary reason fixed rate loans remain the most popular choice among American homebuyers.
The trade-off is that fixed rates are often slightly higher than the initial teaser rates offered on adjustable loans. You pay a premium for certainty. However, that premium can be well worth it if you plan to stay in your home for more than seven years or if you simply value knowing exactly what you owe each month.
Fixed rate mortgages come in several term lengths. A 30 year fixed mortgage offers the lowest monthly payment but the highest total interest cost. A 15 year fixed mortgage has higher monthly payments but saves you tens of thousands of dollars in interest over the life of the loan. Some lenders also offer 10, 20, or 25 year terms to fit different budgets.
When you compare fixed rate options, it helps to see real numbers. Using a mortgage calculator to run different scenarios can show you how much a half percentage point difference in rate actually costs you over time. For example, on a $300,000 loan, dropping from 6.5 percent to 6.0 percent saves roughly $95 per month and over $34,000 in total interest across 30 years.
Adjustable Rate Mortgages: Lower Initial Rates With Future Uncertainty
An adjustable rate mortgage, or ARM, starts with a fixed introductory period, usually 3, 5, 7, or 10 years. During that initial period, your interest rate is lower than what you would get on a comparable fixed rate loan. After the fixed period ends, the rate adjusts periodically, typically once per year, based on a market index plus a margin set by the lender.
The appeal of an ARM is clear: lower payments upfront. If you are confident you will sell or refinance before the fixed period expires, you can save significant money during those early years. For example, a 5/1 ARM might start at 5.5 percent while a 30 year fixed sits at 6.5 percent. On a $350,000 loan, that difference amounts to roughly $220 per month in savings during the first five years.
However, ARMs carry risk. Once the adjustment period begins, your rate could rise substantially. Most ARMs have caps that limit how much the rate can increase at each adjustment and over the life of the loan. A typical structure might be a 2/2/5 cap, meaning the rate can rise no more than 2 percentage points at the first adjustment, 2 percentage points at each subsequent adjustment, and 5 percentage points above the initial rate over the life of the loan.
Understanding these caps is critical. A 5/1 ARM starting at 5.5 percent with a 5 percent lifetime cap could eventually reach 10.5 percent, which would dramatically increase your monthly payment. If you are considering an ARM, make sure you can afford the payment at the highest possible rate.
Key Differences at a Glance
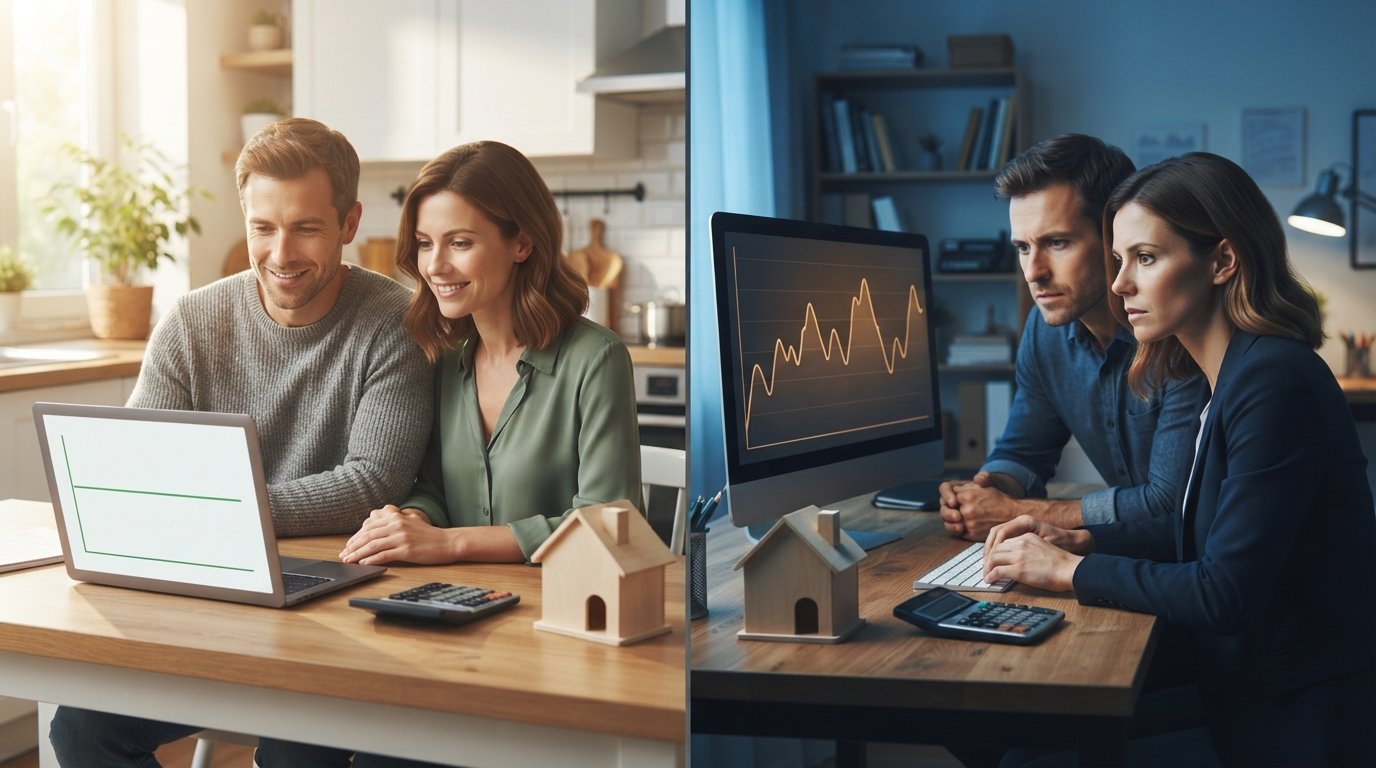
To make a smart decision, you need to understand how these two loan types differ across several dimensions. The comparison below highlights the most important distinctions.
- Interest rate: Fixed stays constant; adjustable changes after the introductory period.
- Monthly payment: Fixed is predictable; adjustable starts lower but can rise significantly.
- Risk: Fixed eliminates rate risk; adjustable exposes you to market fluctuations.
- Best for: Fixed suits long-term homeowners; adjustable suits short-term owners or those expecting income growth.
- Initial cost: Fixed typically has a higher rate; adjustable offers a lower teaser rate.
These differences mean that the better choice depends heavily on your timeline and financial cushion. If you plan to stay in your home for decades, the stability of a fixed rate is hard to beat. If you expect to move or refinance within five to seven years, an ARM could save you meaningful money without exposing you to much risk.
When a Fixed Rate Mortgage Makes Sense
A fixed rate mortgage is often the smarter choice for buyers who prioritize stability and plan to stay in their home for the long term. If you are purchasing a forever home, raising a family, or simply want the peace of mind that comes with knowing your payment will never change, a fixed rate loan delivers that certainty.
Fixed rates also make sense in a rising interest rate environment. If rates are currently low and expected to climb, locking in today's rate protects you from future increases. Even if rates drop later, you can always refinance to a lower rate, though you will pay closing costs to do so.
First-time homebuyers often gravitate toward fixed rate loans because they simplify budgeting. When you are already managing new expenses like property taxes, insurance, and maintenance, having a predictable mortgage payment removes one variable from the equation. For a deeper dive into how these loans compare side by side, see our guide on fixed vs adjustable mortgage decision factors.
When an Adjustable Rate Mortgage Makes Sense
An ARM can be a smart financial move if you have a clear short-term horizon. If you are buying a starter home and plan to sell within five years, or if you are confident you will refinance before the fixed period ends, the lower initial rate can save you thousands of dollars.
ARMs also appeal to buyers in high-price markets where affordability is stretched. The lower initial payment can help you qualify for a larger loan or free up cash for other goals, such as investing or paying down debt. However, you must have a plan for what happens when the rate adjusts.
Consider a hypothetical borrower who takes out a 7/1 ARM at 5.0 percent on a $400,000 loan. For seven years, the payment is based on that low rate. If the borrower sells the home in year six, they never experience an adjustment. The savings compared to a 6.5 percent fixed rate would be substantial. But if the borrower is still in the home in year eight and rates have risen, the payment could jump by hundreds of dollars per month.
How to Decide: A Practical Framework
Choosing between a fixed and adjustable rate mortgage comes down to answering a few key questions about your finances and future plans. Work through the following steps to clarify your decision.
- How long will you stay in the home? If the answer is fewer than seven years, an ARM deserves serious consideration. If it is more than ten years, a fixed rate is usually safer.
- Can you afford the worst-case payment? Calculate what your payment would be at the maximum cap on an ARM. If that number strains your budget, choose a fixed rate.
- How stable is your income? If you expect significant raises or a windfall, an ARM's future increases may be manageable. If your income is flat or unpredictable, lock in a fixed rate.
- What are your refinancing options? If you have good credit and sufficient equity, you may be able to refinance out of an ARM before it adjusts. Just remember that refinancing depends on market conditions and your financial profile at that time.
Running these scenarios with a mortgage calculator can give you concrete numbers to compare. Many borrowers find that the peace of mind from a fixed rate is worth the slightly higher payment, while others appreciate the short-term savings an ARM provides.
The Role of Market Conditions
Interest rate trends influence which loan type is more attractive at any given time. When the yield curve is steep and short-term rates are low, ARMs offer a bigger discount relative to fixed rates. When the curve is flat, the savings from an ARM may be minimal, making a fixed rate the better value.
In a rising rate environment, fixed rates become more appealing because they lock in today's cost before rates climb further. In a falling rate environment, some borrowers choose ARMs expecting to refinance later at even lower rates. However, predicting rate movements is notoriously difficult, so it is wise not to base your decision solely on forecasts.
Instead, focus on what you can control: your budget, your timeline, and your risk tolerance. These personal factors matter far more than trying to time the market.
Common Mistakes to Avoid
Many borrowers make avoidable errors when choosing between fixed and adjustable loans. One frequent mistake is focusing only on the initial rate without considering the long-term cost. A low teaser rate can be enticing, but if you end up paying a much higher rate after the adjustment period, you may lose money overall.
Another mistake is failing to read the fine print on ARM caps and adjustment schedules. Some ARMs adjust every six months rather than annually, and some have higher lifetime caps than others. Understanding these details before you sign is essential.
Finally, some borrowers assume they will definitely refinance before their ARM adjusts, but life circumstances can change. Job loss, illness, or a drop in home value can make refinancing difficult or impossible. Always have a backup plan.
Getting Personalized Quotes
The best way to determine which loan type offers the better deal for your situation is to compare personalized quotes from multiple lenders. Rates and terms vary significantly between lenders, and the difference can amount to thousands of dollars over the life of your loan.
Platforms like RateChecker allow you to see real-time mortgage rate comparisons and explore different loan options side by side. This kind of transparency helps you make an informed decision rather than guessing.
When you request quotes, be sure to ask for both fixed and adjustable options so you can compare them directly. Provide accurate information about your credit score, down payment, and desired loan amount to get the most reliable estimates. And do not be afraid to negotiate; lenders often compete for your business.
Ultimately, the choice between a fixed and adjustable rate mortgage is a personal one. There is no universally correct answer. By understanding the trade-offs and evaluating your own circumstances, you can select the loan that best supports your financial goals and gives you confidence in your homeownership journey.