Mortgage for Self Employed Borrowers with Variable Income
Lenders average two years of tax returns to qualify self employed borrowers. Learn how variable income is calculated and how to strengthen your application.
By Benjamin Reed
Your income arrives in uneven waves: a strong quarter, then a slow stretch, then a record month that makes up for both. That pattern is normal for business owners, freelancers, and commission-based professionals, but it can feel like a roadblock when you want to buy a home. The good news is that lenders do not require a predictable paycheck. They require proof that your income is real, stable, and likely to continue. Understanding how underwriters read variable income is the first step toward a mortgage for self employed borrowers with variable income that actually fits your financial life. This guide walks through the calculation methods, the documentation that matters, and the loan options designed for people whose earnings do not arrive on a fixed schedule.
How Lenders Calculate Qualifying Income When Your Earnings Fluctuate
When a lender reviews a salaried borrower, the math is simple: take the annual salary and divide by twelve. When the borrower is self employed, the process becomes a forensic exercise. Underwriters want to see a two-year history, usually documented through federal tax returns, and they will average those years to smooth out spikes and dips. If your income is rising, some lenders will use the most recent year, but only when the trend is clearly upward and supported by the rest of your file. If income is declining, expect the lender to use the lower figure or ask for a detailed explanation.
The two-year average is not a punishment. It is a risk-management tool that protects both you and the lender from basing a long-term obligation on a single unusually good year. For a mortgage for self employed borrowers with variable income, the average becomes the foundation of your borrowing power. That means a banner year followed by a modest year may produce a qualifying income that is lower than either one individually. Planning around that average, rather than your best month, keeps your budget realistic.
Profit-and-loss statements matter as well, especially for borrowers who have been in business for less than two years or who use a stated-income approach. A profit-and-loss statement prepared by a bookkeeper or CPA can show the lender how the business is performing in real time, even before the tax return is filed. Some lenders will accept a year-to-date profit-and-loss statement alongside one year of tax returns, while others require a full two years of returns. The key is to ask upfront which documents a given lender will accept, because the definition of qualifying income varies from one program to the next.
Why Write-Offs Can Quietly Lower Your Borrowing Power
Every legitimate business deduction reduces your tax bill, and that is a good thing. But the same deduction reduces the income that appears on your tax return, and the mortgage lender reads that number closely. If you write off a home office, a vehicle, meals, or equipment, those expenses lower your net profit. A lower net profit translates into a lower qualifying income, which translates into a smaller loan amount. Many self employed borrowers are surprised to learn that aggressive tax planning can shrink their purchasing power by tens of thousands of dollars.
There is no single right answer here. Some borrowers choose to reduce deductions for one or two years before applying, accepting a higher tax bill in exchange for a larger loan. Others keep their deductions and adjust their home search accordingly. The important move is to model both scenarios. Ask your tax professional to estimate your net profit under your current strategy and under a leaner deduction strategy, then compare the resulting loan amounts. A mortgage calculator can help you translate those income figures into estimated monthly payments, and a loan officer can pre-qualify you under each scenario so you see the trade-off in real numbers.
It also helps to separate business expenses from personal ones with clean bookkeeping. When a lender sees commingled funds or vague categories, the underwriter may exclude more income than necessary. Clear records, categorized expenses, and a consistent accounting method make it easier for the lender to accept your numbers at face value. In a mortgage for self employed borrowers with variable income, documentation quality often matters as much as the income itself.
Bank Statement Loans: A Real Alternative With Real Trade-Offs
For borrowers whose tax returns show modest income because of deductions or business structure, bank statement loans offer a path that does not rely on tax returns at all. Instead, the lender reviews twelve or twenty-four months of personal or business bank statements and calculates an average monthly deposit figure. That average becomes the qualifying income. The appeal is obvious: you can use the money that actually flows through your accounts, even if your tax return tells a more conservative story.
The trade-offs are equally real. Bank statement loans typically carry higher interest rates than conventional loans, and they often require larger down payments, sometimes twenty percent or more. They are also less standardized, which means underwriting guidelines vary widely from lender to lender. Some lenders want business statements, others accept personal statements, and the expense factors they apply can differ significantly. Before you pursue this route, gather at least two years of statements and ask each lender to explain exactly how they calculate qualifying income from deposits.
Bank statement loans are not the only option. Asset depletion loans, which convert eligible assets into a monthly income stream, can work for borrowers with substantial savings. Stated income programs exist in some niches, though they usually come with higher rates and stricter credit requirements. The right choice depends on your income pattern, your reserves, and your long-term plans. Comparing quotes from multiple lenders is the only reliable way to see how each program prices your situation. On RefinancingCo, you can review mortgage tools and educational resources that help you weigh these alternatives before you commit.
Preparing a Documentation Packet Before You Request Quotes
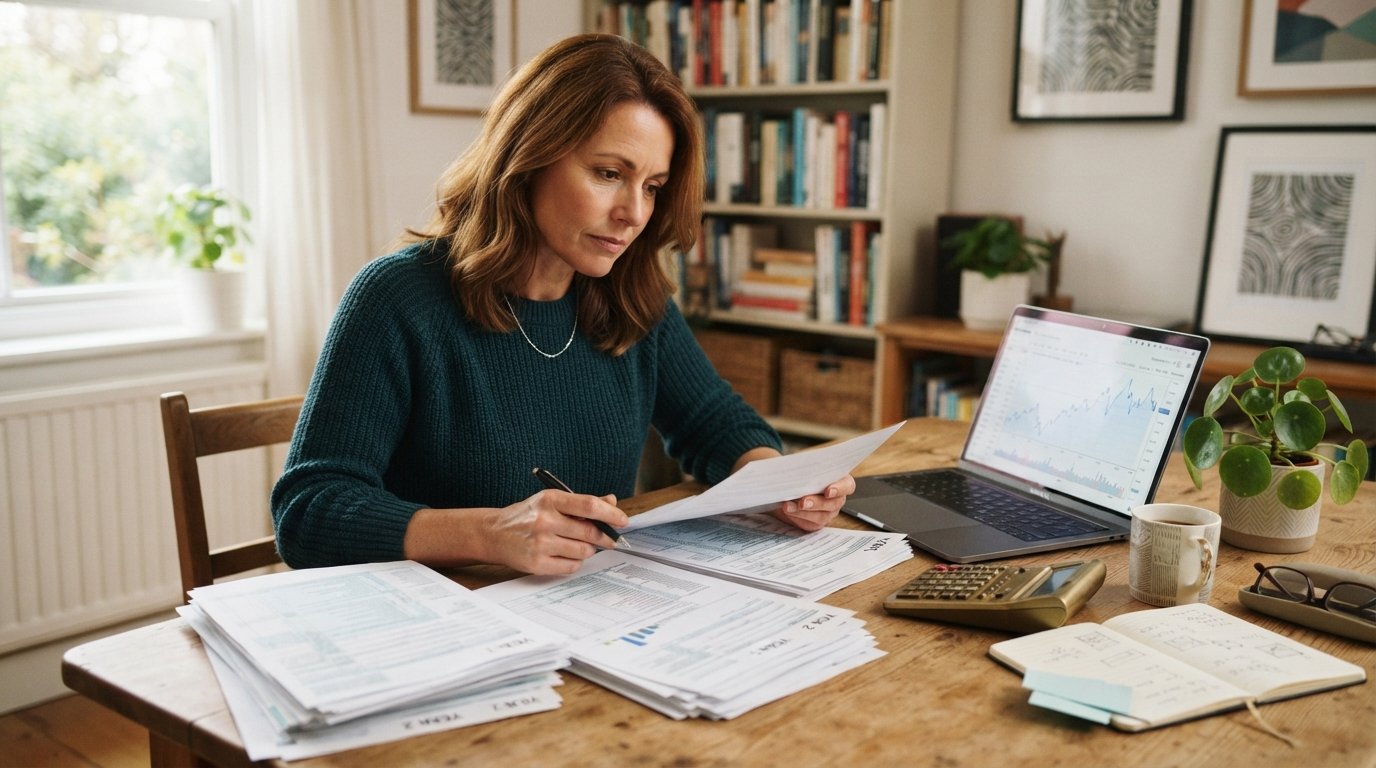
The strongest application is the one that leaves nothing for the underwriter to guess. Before you request quotes, assemble a packet that tells a complete story about your income. Lenders will ask for different combinations of documents, but a thorough packet shortens the process and reduces the chance of a last-minute denial. Think of it as a resume for your finances: it should be organized, consistent, and easy to verify.
Start with the core documents. Most lenders will want the following items, and having them ready puts you in a stronger position when you compare offers:
- Two years of personal federal tax returns with all schedules and W-2s or 1099s
- Two years of business tax returns, including K-1s, if your business files separately
- Year-to-date profit-and-loss statement prepared by you or your accountant
- Two to three months of business and personal bank statements
- A letter explaining your business, your role, and any large or unusual deposits
Beyond the core documents, prepare a short narrative about your income history. If one year was unusually low because of a one-time expense or a market slowdown, explain it in plain language. If your income is rising, point to contracts or client commitments that support the trend. Underwriters are trained to look for red flags, and a clear explanation prevents a legitimate fluctuation from being read as instability. In our guide on how self employed borrowers qualify for a mortgage, we cover additional tips for presenting your income story effectively.
Finally, keep your packet consistent. The income figure on your loan application should match the figure on your tax returns and your profit-and-loss statement. Discrepancies invite scrutiny and delay. If your bookkeeper uses a different accounting method than your tax preparer, reconcile the numbers before you apply. A clean, consistent packet is one of the most effective ways to improve your odds of approval for a mortgage for self employed borrowers with variable income.
Choosing the Right Loan Program for Irregular Earnings
Not every loan program treats variable income the same way. Conventional loans, backed by Fannie Mae and Freddie Mac, allow self employed income but apply strict rules about tax return analysis and deduction add-backs. FHA loans are more forgiving in some areas, though they still require full documentation. VA loans can be flexible for veteran business owners, and USDA loans serve rural borrowers with their own income rules. The right program depends on your credit score, your down payment, your reserves, and the way your income is structured.
It is worth comparing at least three quotes before you choose. A mortgage for self employed borrowers with variable income can vary by more than a full percentage point in rate between lenders, and that difference translates into meaningful savings over the life of the loan. Ask each lender how they calculate qualifying income, whether they will use a profit-and-loss statement, and what documentation they require. Lenders that specialize in self employed borrowers often have more flexible guidelines than banks that focus on salaried employees.
Also consider how much house you actually need. A pre-approval based on your two-year average may be lower than the amount you hoped for, but it protects you from a payment that strains your budget during a slow season. Build a cushion into your monthly plan, and keep business and personal finances separate so your records stay clean for future refinancing or home equity needs. With the right preparation, variable income does not close the door to homeownership. It simply changes the path you take to get there.