Mortgage Pre-Approval Letter vs Pre-Qualification: Key Difference
Understand the mortgage pre-approval letter vs pre-qualification difference and how a verified pre-approval strengthens your offer and budget.
By Olivia Keller
When you start shopping for a home, two terms get tossed around constantly: pre-qualification and pre-approval. They sound similar, and plenty of buyers use them interchangeably, but the gap between them is wide enough to change how sellers treat your offer, how much house you can realistically afford, and how smoothly your loan closes. Understanding the mortgage pre-approval letter vs pre-qualification difference early in the process saves you time, prevents heartbreak after a seller rejects your bid, and puts you in a stronger negotiating position. This guide breaks down exactly what each step involves, why real estate agents and listing agents react to them differently, how long a pre-approval stays valid, and what can cause a lender to revisit your approval before closing.
What Pre-Qualification Actually Means
Pre-qualification is a quick, informal estimate of how much you might be able to borrow. It usually involves a short conversation or online form where you share basic details: your income, monthly debts, assets, and the down payment you plan to use. Many lenders offer pre-qualification with no credit check or a soft pull that does not affect your score. The output is a ballpark figure, not a commitment. It gives you a rough budget to start browsing homes and a sense of whether your financial profile is in the right range for a mortgage.
Because pre-qualification relies on self-reported information, it carries little weight. A lender has not verified your income documents, reviewed your tax returns, or pulled a full credit report. The number you receive is an estimate that can shift significantly once real underwriting begins. That does not make pre-qualification useless. It is a low-pressure way to start the conversation, especially for first-time buyers who are still learning how lenders evaluate borrowers.
Think of pre-qualification as a rough sketch. It tells you the general shape of what you can afford, but it is not a finished blueprint. If you are months away from buying or just exploring options, a pre-qualification can help you set expectations. If you are ready to make offers, it is not enough on its own.
What a Mortgage Pre-Approval Letter Involves
A mortgage pre-approval letter is a formal, written conditional commitment from a lender. It states that, based on a thorough review of your financial documents, the lender is willing to lend you a specific amount, subject to conditions like a satisfactory appraisal, clear title, and a final income verification. To issue a pre-approval, the lender typically verifies your income and employment, pulls your full credit report, reviews your bank statements and asset documents, and runs your file through an automated underwriting system. The process is more involved and usually takes a few days rather than a few minutes.
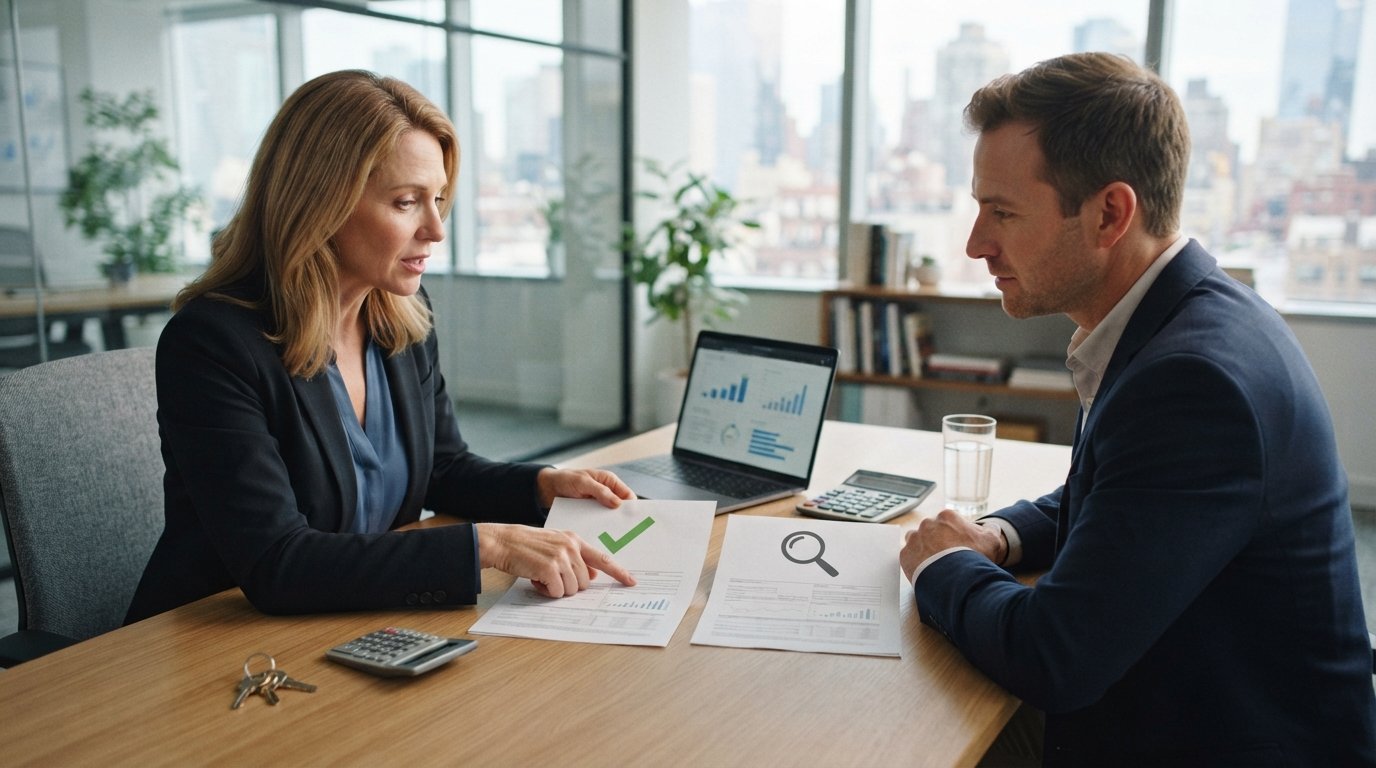
The result is a letter you can attach to an offer. It signals to sellers and their agents that a lender has already scrutinized your finances and believes you can close. That credibility is the core of the mortgage pre-approval letter vs pre-qualification difference: one is an estimate, the other is a verified statement of lending willingness. In competitive markets, sellers often discard offers without a pre-approval letter attached, no matter how attractive the price.
If you want a detailed walkthrough of the documents involved and the timeline, our guide on how the mortgage preapproval process works covers each stage from application to letter issuance. The key takeaway is that pre-approval requires proof, not promises.
Key Differences: Verification Depth and Weight
The most important distinction between pre-qualification and pre-approval is the depth of verification. Pre-qualification is based largely on what you tell the lender. Pre-approval is based on what the lender confirms. That difference in verification changes how much weight the letter carries with everyone involved in the transaction.
- Credit check: Pre-qualification often uses a soft credit pull or none at all; pre-approval involves a hard credit inquiry and a full report review.
- Income and asset verification: Pre-qualification relies on self-reported figures; pre-approval requires pay stubs, W-2s, tax returns, and bank statements.
- Underwriting review: Pre-qualification is not underwritten; pre-approval goes through an automated underwriting system and often a human underwriter.
- Commitment level: Pre-qualification is an estimate with no commitment; pre-approval is a conditional commitment to lend a specific amount.
Those four differences explain why sellers and real estate agents treat a pre-approval letter more seriously. A listing agent reviewing multiple offers will typically advise the seller to prioritize buyers with a pre-approval letter because the risk of financing falling through is lower. An offer with only a pre-qualification may be viewed as speculative, and in a multiple-offer situation, it may not even be presented to the seller.
For buyers, the practical consequence is negotiating power. A pre-approval letter strengthens your offer, can reduce the chance a seller demands a higher earnest money deposit to compensate for financing risk, and may give you more room to negotiate on repairs or closing costs. It also helps your real estate agent move quickly when the right home appears, because you are not waiting on a lender to start the process from scratch.
How Long a Pre-Approval Letter Stays Valid
A pre-approval letter is not permanent. Most lenders consider it valid for 60 to 90 days, though some extend to 120 days. The expiration reflects the reality that your financial situation, credit profile, and the market can change. After the validity window closes, the lender will need to refresh your file before you can make a new offer with the same letter.
Several situations call for a refresh even within the validity period. If your income changes, you take on new debt, you change jobs, or you make a large purchase that affects your cash reserves, the lender may need to re-verify your qualifications. Rate locks also have their own timelines, separate from the pre-approval letter. A rate lock protects your interest rate for a set period, while the pre-approval letter confirms your borrowing capacity. Both matter, and both can expire.
If your home search extends beyond the initial window, ask your lender about the refresh process. Some lenders issue updated letters quickly, especially if your financial situation has not changed. Others may require new documentation. Building a relationship with a responsive lender early makes this step easier, and comparing offers from multiple participating lenders through a platform like MortgageZone can help you find one that fits your timeline.
What Can Cause a Pre-Approval to Be Re-Evaluated Before Closing
Even a solid pre-approval letter does not guarantee final loan approval. Lenders can and do re-evaluate your file before closing, and certain changes raise red flags. The most common triggers include:
- New debt: Opening a credit card, financing a car, or taking out a personal loan after pre-approval increases your debt-to-income ratio and can push you over the lender's threshold.
- Job or income changes: Switching from a salaried position to self-employment, changing industries, or losing a job can undermine the income verification your pre-approval was based on.
- Large or unexplained deposits: Underwriters want to see a paper trail for big deposits. Cash gifts, sudden transfers, or unexplained funds can delay or derail approval.
- Appraisal issues: If the home appraises below the purchase price, the lender may adjust the loan amount or require a larger down payment.
- Credit score drops: A late payment or a new collection account between pre-approval and closing can change your eligibility or your rate.
The lesson is simple: once you have a pre-approval letter, treat your finances as if they are under a microscope. Avoid major purchases, job changes, and new credit accounts until after closing. Keep your documents organized and respond quickly to lender requests. A pre-approval is a strong signal, but it is conditional, and the conditions are real.
Which Step Should You Start With?
For most buyers, pre-approval is the step that matters. Pre-qualification can be a useful first conversation if you are early in the process, but it will not carry weight when you make an offer. If you are serious about buying within the next few months, go straight to pre-approval. The extra documentation and wait time are worth it because the letter gives you credibility and a clear budget.
First-time buyers often benefit from starting with education and comparison. MortgageZone connects you with participating lenders who can guide you through pre-approval, compare loan options, and help you understand what you qualify for. Because MortgageZone is not a lender, its role is to simplify the process and let you request personalized quotes from multiple Network Members. That comparison can reveal differences in rates, fees, and pre-approval timelines that matter for your budget.
If you are also weighing refinancing options down the road, resources like RefinancingCo offer additional mortgage tools and educational content that complement the home purchase process. For now, focus on getting pre-approved before you shop, and keep your financial profile stable until closing.
Practical Steps to Get Pre-Approved
Getting pre-approved is a straightforward process if you prepare ahead of time. The steps below outline what to expect and how to move through them efficiently.
- Gather your documents: Recent pay stubs, W-2s, tax returns, bank statements, and identification. Self-employed buyers should have profit-and-loss statements and business returns ready.
- Compare lenders: Rates and fees vary. Request quotes from multiple participating lenders through MortgageZone to see how your options stack up.
- Complete the application: Provide your financial details and authorize a credit check. Expect a hard inquiry on your credit report.
- Respond to underwriting requests: The lender may ask for additional documentation or clarification. Quick responses keep the process moving.
- Receive your letter: Review the approved amount, conditions, and expiration date. Ask questions if anything is unclear.
Once you have the letter, share it with your real estate agent and attach it to offers. Keep a copy for your records and note the expiration date so you know when to refresh it. If your search takes longer than expected, contact your lender before the letter expires rather than after.
Common Misconceptions About Pre-Qualification and Pre-Approval
One common myth is that pre-qualification and pre-approval are the same thing with different names. They are not. A pre-qualification is an estimate; a pre-approval is a verified conditional commitment. Treating them as interchangeable can lead to disappointment when a seller rejects an offer or when underwriting uncovers issues that a pre-qualification never checked.
Another misconception is that a pre-approval letter guarantees financing. It does not. It is conditional on the property appraising, the title being clear, and your financial situation remaining stable. Buyers who understand the conditions are better prepared to protect their approval and close on time.
A third myth is that pre-approval hurts your credit score. A single hard inquiry has a small, temporary effect. Shopping for rates within a short window is typically treated as one inquiry by credit scoring models, so comparing lenders is not penalized the way multiple unrelated credit applications would be.
Finally, some buyers believe pre-qualification is enough in a slow market. Even in cooler markets, sellers prefer offers with pre-approval letters because they reduce the risk of a deal falling apart. The stronger your documentation, the more seriously your offer is treated.
How Pre-Approval Fits Into Your Overall Home Buying Plan
Pre-approval is not just a piece of paper; it is a planning tool. It tells you your realistic price range, helps you set a budget that includes taxes, insurance, and closing costs, and gives you a timeline for your search. It also positions you to move quickly when you find the right home, which matters in competitive situations.
As you plan, keep the mortgage pre-approval letter vs pre-qualification difference in mind when you talk to lenders and agents. Ask directly whether the letter you are receiving is a pre-qualification or a pre-approval, and what conditions apply. Clear communication upfront prevents surprises later.
When you are ready to compare lenders and request pre-approval guidance, MortgageZone's network of participating lenders can provide quotes tailored to your situation. The platform is designed to simplify the process, so you can focus on finding the right home rather than untangling mortgage jargon. Start with pre-approval, keep your finances steady, and you will be in a stronger position to negotiate and close with confidence.