Reverse Mortgage Counseling: What to Expect in 2026
Reverse mortgage counseling requirement what to expect: learn the steps, costs, and key questions to ask before you commit.
If you are 62 or older and considering a reverse mortgage, you have likely heard about the mandatory counseling requirement. It is not just a formality: it is a federally required step designed to protect you from costly mistakes. Understanding what happens during counseling, what questions to ask, and how it fits into the overall loan process can turn a confusing obligation into a valuable planning tool. This guide walks you through the reverse mortgage counseling requirement, what to expect step by step, and how to prepare so you leave the session with clarity and confidence.
Why HUD-Approved Counseling Is Required for HECM Loans
The Home Equity Conversion Mortgage (HECM) is the most common reverse mortgage, insured by the Federal Housing Administration (FHA) and overseen by the U.S. Department of Housing and Urban Development (HUD). Since 2000, HUD has required that every borrower complete counseling with a HUD-approved agency before applying for a HECM. This requirement exists because reverse mortgages are complex financial products with long-term consequences for your home, your heirs, and your retirement budget.
Unlike a traditional mortgage, a reverse mortgage does not require monthly principal and interest payments. Instead, the loan balance grows over time, and repayment is typically deferred until the last borrower moves out, sells the home, or passes away. While that can provide valuable cash flow in retirement, it also means that failing to pay property taxes, homeowners insurance, or HOA dues can lead to foreclosure. Counseling ensures you understand these obligations before you sign.
The requirement applies to all HECM loans, whether you choose a fixed-rate lump sum or an adjustable-rate line of credit. Some proprietary reverse mortgages (jumbo loans not insured by FHA) may not require counseling, but most lenders strongly encourage it. If you are exploring a HECM, expect the counseling certificate to be a mandatory part of your application file.
What Happens During a Reverse Mortgage Counseling Session
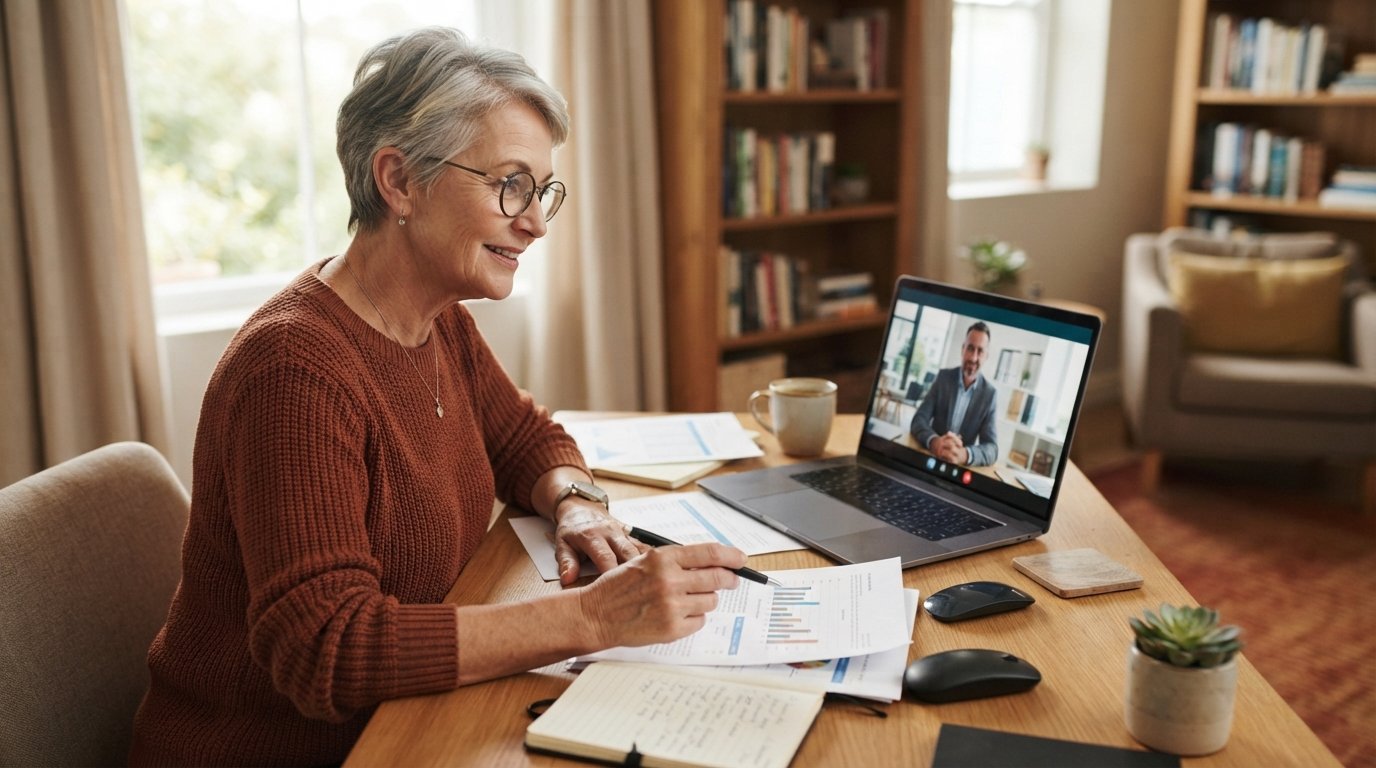
Counseling is not a sales pitch. It is an educational session, typically lasting 60 to 90 minutes, conducted by a trained counselor at a HUD-approved nonprofit or government agency. You can meet in person, by phone, or online. The counselor's job is to help you evaluate whether a reverse mortgage is right for your situation, not to push you toward a loan.
During the session, the counselor will walk you through the following topics, often using a standardized curriculum and a budget analysis. You will receive a certificate of completion at the end, which you must present to your lender. The certificate is valid for a limited time (usually 180 days), so timing matters.
Here is what to expect during a typical counseling session:
- Overview of reverse mortgage types: The counselor explains the differences between HECM loans and proprietary products, including fixed vs. adjustable rates and lump sum vs. line of credit payouts.
- Costs and fees: You will review upfront costs such as the initial mortgage insurance premium, origination fee, closing costs, and ongoing servicing fees, plus the interest that accrues over time.
- Financial assessment: The counselor will discuss your income, expenses, and credit history to help you understand whether you can afford to stay current on property charges.
- Alternatives: You will compare a reverse mortgage to other options, such as selling your home, downsizing, using a home equity loan, or applying for government assistance.
- Your obligations: The counselor emphasizes that you must continue paying property taxes, insurance, and HOA dues, and maintain the home in good condition.
After the session, the counselor will provide a written report or certificate. You are encouraged to take notes and ask questions at any point. The counselor cannot recommend a specific lender or loan product, but they can help you understand the trade-offs. If you are considering a reverse mortgage, it is wise to gather quotes from multiple lenders after counseling. MortgageZone can help you compare offers from participating lenders in its network, giving you a clearer picture of rates and fees.
It is also important to know that counseling is not a one-way lecture. The counselor will ask about your goals, your budget, and your long-term plans. They may ask whether you intend to stay in the home for many years, whether you have heirs who might want to keep the property, and how you would handle unexpected expenses. These questions are designed to surface potential risks before you commit.
Questions to Ask About Costs, Obligations, and Payout Options
To get the most from your counseling session, arrive with a list of questions. The counselor is there to help you understand the fine print, so do not hesitate to ask for clarification. Below are key questions to ask, grouped by topic. Use them as a starting point and add your own based on your circumstances.
Costs and fees:
- What is the total upfront cost, including origination, closing, and mortgage insurance premiums?
- How much will I pay in ongoing servicing fees each month?
- How does the interest rate work, and how will my loan balance grow over time?
- Are there any penalties for paying off the loan early or for changing payout options?
Obligations and risks:
- What happens if I fail to pay property taxes or homeowners insurance?
- Can the lender foreclose if I live in a nursing home for more than 12 months?
- What are the rules about maintaining the property, and how often are inspections required?
- How does a reverse mortgage affect my eligibility for Medicaid or other government benefits?
Payout options and financial assessment:
- What payout options are available (lump sum, monthly payments, line of credit, or a combination)?
- How does the financial assessment determine whether I need a set-aside for taxes and insurance?
- What is a Life Expectancy Set-Aside (LESA), and will I be required to have one?
- How do I access funds from a line of credit, and can the line grow over time?
These questions will help you compare offers with confidence. If a lender or counselor cannot answer them clearly, that is a red flag. Remember that counseling is an educational service, not a commitment. You can take your certificate to any participating lender.
For a deeper look at the risks and drawbacks of reverse mortgages, see our guide on reverse mortgage disadvantages and key risks. It covers common pitfalls such as foreclosure from unpaid property charges and the impact on inheritances.
Financial Assessment and Set-Aside Requirements
Since 2015, HUD has required lenders to perform a financial assessment for all HECM borrowers. The assessment evaluates your income, credit history, and cash flow to determine whether you can afford to pay property taxes, homeowners insurance, and other property charges. If the lender concludes that you may struggle to meet these obligations, they may require a set-aside, known as a Life Expectancy Set-Aside (LESA).
A LESA is a portion of your loan proceeds reserved to pay property taxes and insurance on your behalf. The amount is based on your age, the value of your home, and the estimated cost of those charges over your life expectancy. While a LESA reduces the amount of cash you can access upfront, it also protects you from accidental foreclosure due to unpaid taxes or insurance.
During counseling, you will discuss the financial assessment process and what documents you may need to provide. The counselor can help you understand how a LESA works and whether it might apply to you. They may also suggest steps to improve your financial profile, such as paying down debts or increasing income documentation.
It is important to note that the financial assessment is not a credit score requirement in the traditional sense. Lenders are not looking for perfect credit; they are looking for a history of paying bills on time and enough residual income to cover property charges. If you have experienced credit issues, be prepared to explain them and provide documentation.
Documents to Gather Before and After Counseling
To make your counseling session productive, gather key documents in advance. The counselor may not need to see all of them, but having them on hand will help you answer questions accurately and identify any potential issues early. After counseling, you will need additional documents for the lender's financial assessment and loan application.
Before counseling, gather:
- Your most recent mortgage statement, including your outstanding balance and monthly payment (if any).
- Recent property tax bill and homeowners insurance policy.
- Proof of income, such as Social Security statements, pension statements, or investment account statements.
- A list of your monthly expenses, including utilities, food, healthcare, and debt payments.
- Any documents related to other assets, such as savings accounts, CDs, or stocks.
After counseling, you will need for the lender:
- Your counseling certificate (proof of completion).
- Government-issued photo ID and proof of age (for all borrowers).
- Social Security numbers for all borrowers.
- Current mortgage statement and any other lien documents.
- Homeowners insurance policy and property tax bill.
- Proof of income and asset documentation for the financial assessment.
- Credit report authorization and explanation letters for any derogatory items.
Having these documents ready can speed up the process and reduce back-and-forth with your lender. It also helps the counselor give you more tailored advice during the session.
For a broader resource on mortgage tools and lender comparisons, visit RefinancingCo, which offers educational content and calculators to help you navigate home loan decisions.
How Counseling Fits Into the Reverse Mortgage Process
Counseling is typically the first formal step in the reverse mortgage journey. You can complete it before or after you receive a loan estimate, but it must be done before you submit a full application. The certificate is valid for a limited period, so coordinate with your lender to avoid delays.
After counseling, the process generally follows these stages:
- Receive loan estimates: Compare offers from multiple lenders, paying attention to interest rates, fees, and payout options.
- Complete the financial assessment: Provide documentation and undergo a credit check; the lender determines if a LESA is needed.
- Underwriting and appraisal: The lender orders an appraisal to confirm your home's value and reviews your application.
- Closing: You sign the final loan documents, and funds are disbursed according to your chosen payout method.
Keep in mind that you have a three-day right of rescission after closing, during which you can cancel the loan for any reason. Counseling helps you understand this right and other consumer protections.
If you are ready to explore reverse mortgage options, MortgageZone can connect you with participating lenders who offer HECM and other products. You can request personalized quotes and compare terms side by side, all from the comfort of your home.
Common Myths and Misconceptions About Counseling
Despite its importance, counseling is often misunderstood. Some borrowers worry that counseling is a sales tactic or that it will pressure them into a loan. In reality, HUD-approved counselors are prohibited from steering you toward a specific lender or product. Their role is to educate, not to sell.
Another myth is that counseling is expensive. In fact, many HUD-approved agencies offer counseling at low or no cost, and some lenders will reimburse the fee at closing. The cost is typically modest (around $125 to $200) and is well worth the clarity it provides.
Some borrowers also believe that counseling is a one-time formality that can be skipped if they already understand reverse mortgages. However, the certificate is mandatory for HECM loans, and lenders cannot proceed without it. Skipping counseling is not an option if you want a HECM.
Finally, some people think counseling will disqualify them from a reverse mortgage. On the contrary, counseling helps you determine whether you qualify and whether a reverse mortgage is a good fit. It may reveal that a different option, such as a home equity loan or downsizing, is better for your situation. That is a valuable outcome, not a failure.
By approaching counseling with an open mind and a list of questions, you can turn a required step into a powerful planning tool. It is your opportunity to get unbiased answers about costs, risks, and alternatives before you make a long-term commitment.
Reverse mortgage counseling is more than a checkbox: it is a safeguard for your financial future. With the right preparation, you can complete the requirement efficiently and gain the confidence to make an informed decision. Whether you ultimately choose a reverse mortgage or another path, the knowledge you gain will serve you well.