Reverse Mortgage Mandatory Obligations and Financial Assessment Guide
Understand reverse mortgage mandatory obligations and financial assessment, including set-asides, residual income rules, and documents to prepare.
By Landon Hayes
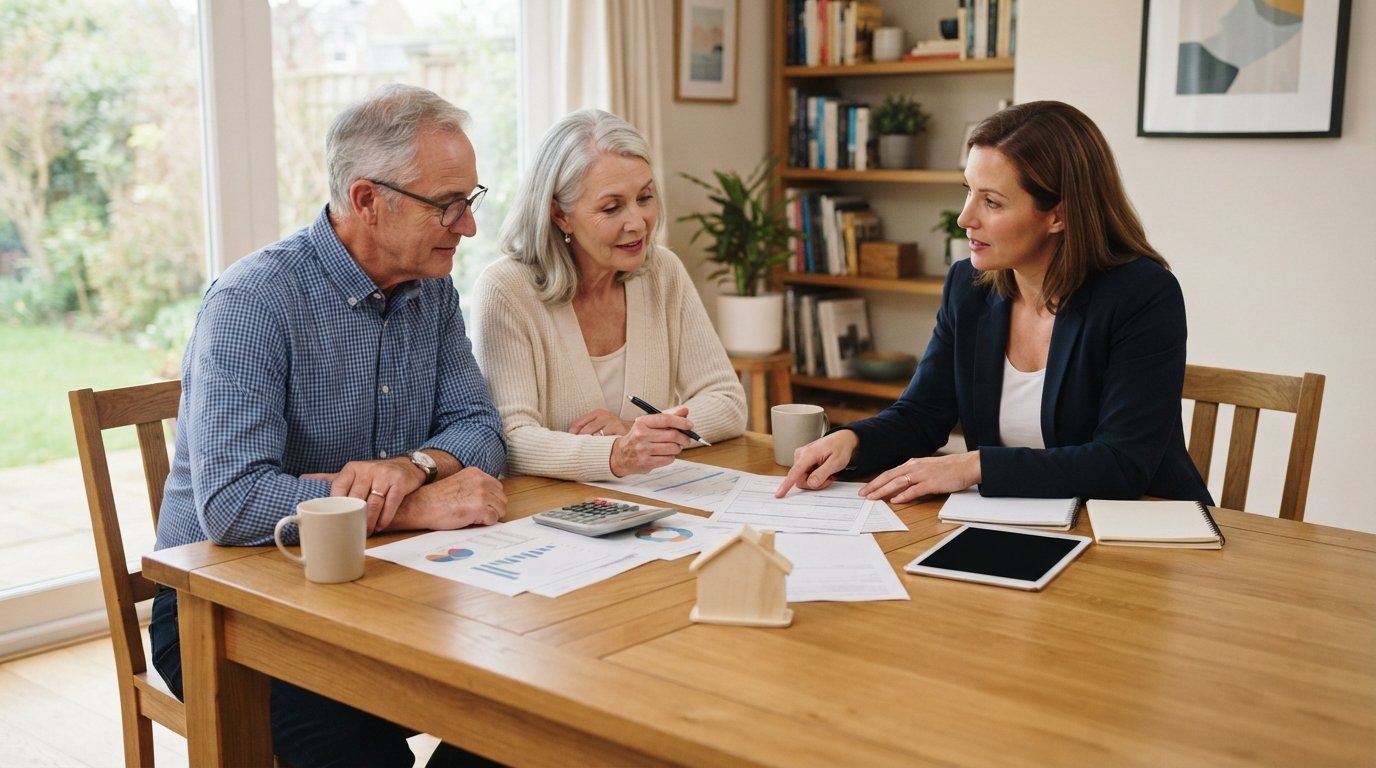
The reverse mortgage financial assessment is not a formality. It is the step where your lender looks at your income, expenses, credit history, and property charges to decide whether you can keep up with the mandatory obligations that come with a reverse mortgage. For many homeowners aged 62 and older, this is the moment when the loan either moves forward smoothly or stalls because of a tax bill, an insurance premium, or a thin budget. Understanding what the assessment reviews, how set-asides are calculated, and what to do if your residual income looks tight can save you weeks of delay and help you avoid a denied application.
What the Reverse Mortgage Financial Assessment Reviews and Why It Exists
The financial assessment is a underwriting step required for Home Equity Conversion Mortgages (HECMs), the most common type of reverse mortgage. It was introduced to protect borrowers and the government insurance fund from loans that fail because the homeowner cannot pay property taxes, homeowners insurance, or other mandatory charges. When those charges go unpaid, the loan can go into default and eventually face foreclosure, which defeats the purpose of a reverse mortgage designed to help seniors stay in their homes.
During the assessment, the lender reviews your income sources, your monthly expenses, your credit history, and your payment history on housing-related costs. The lender is not looking for perfect credit. Instead, it is looking for a reasonable pattern of paying obligations on time and enough residual income to cover the mandatory obligations that continue after the loan closes. Those mandatory obligations include property taxes, homeowners insurance, flood insurance if required, homeowners association dues, and any required repairs or maintenance that keep the home in good condition.
The assessment also examines whether you have enough money left over each month after paying your regular living expenses. This leftover amount is called residual income, and it is a key metric in the approval decision. Lenders use a residual income guideline based on household size and region, but they also have discretion to approve loans with compensating factors such as significant cash reserves, a strong credit history, or a documented plan to pay property charges from a set-aside account. In our guide on Charlotte NC mortgage guide: rates and tips for 2026, we explain how local market conditions and lender guidelines can affect approval outcomes, and the same principle applies here: the numbers matter, but so does the full picture of your financial situation.
Why does this matter for you? Because a reverse mortgage does not eliminate the costs of homeownership. You still owe property taxes and insurance, and if you fall behind, the lender can call the loan due. The financial assessment is the lender's way of confirming that you have a workable plan to meet those obligations for the long term. It is also your opportunity to spot budget gaps before they become problems.
How Set-Asides for Taxes and Insurance Are Determined
A set-aside is money reserved from your reverse mortgage proceeds to pay future property charges. Lenders calculate set-asides when the financial assessment shows that your income is not enough to cover mandatory obligations comfortably. The set-aside amount is based on the expected cost of property taxes, homeowners insurance, flood insurance, and HOA dues over the life of the loan, plus a cushion for increases.
The calculation starts with the current annual cost of each mandatory obligation. The lender then projects those costs forward using assumed inflation rates and life expectancy tables. For a 70-year-old borrower, the projection period might be 20 years or more. The total projected cost is then set aside from the loan proceeds, which reduces the amount of money available to you as a lump sum, monthly payment, or line of credit.
There are two main types of set-asides. A fully funded set-aside covers all projected property charges for the life of the loan. A partially funded set-aside covers a shorter period, often because the borrower has some income to contribute toward those costs. Some borrowers choose to pay their property taxes and insurance directly and decline a set-aside, but only if the financial assessment shows they have enough residual income to handle those payments. The lender will verify this through bank statements, tax returns, and insurance declarations.
Here is a simple way to think about the trade-off: a larger set-aside gives you more protection against rising taxes and insurance, but it reduces the cash you can access. A smaller set-aside preserves more proceeds but requires you to manage those bills yourself. The right choice depends on your budget, your risk tolerance, and how stable your income sources are. If you are unsure, ask the lender to run scenarios with different set-aside amounts so you can compare the impact on your available funds.
What Happens If the Assessment Finds Limited Residual Income
A limited residual income finding does not automatically mean denial. Lenders have several tools to work with, and the outcome depends on the specifics of your situation. The first option is a set-aside, as described above. By reserving money for taxes and insurance, the lender reduces the strain on your monthly budget and can approve the loan even if your residual income is below the guideline.
The second option is to document compensating factors. These can include a history of on-time payments on housing expenses, a substantial savings account, or a family member who has agreed to help with property charges. Lenders may also consider a documented plan to reduce expenses, such as a reverse mortgage that pays off credit card debt and lowers your monthly obligations. Each lender weighs these factors differently, so it helps to shop around and compare quotes from multiple lenders in the MortgageZone network.
If the assessment still shows a shortfall, the lender may deny the application. In that case, you have options. You can reduce your debt load before reapplying, add a co-borrower who has income, or explore a different loan product. A home equity loan or a cash-out refinance might not eliminate monthly payments, but it could provide the funds you need without the same financial assessment requirements. The key is to avoid rushing into a loan that you cannot sustain. A denial is a signal to revisit your budget, not a permanent barrier.
It is also worth noting that the financial assessment is not a one-time event. Lenders may re-verify your financial situation at closing, and servicers monitor whether you stay current on property charges. If your circumstances change, such as a large medical bill or a drop in income, you should contact your servicer early to discuss options before a delinquency occurs.
Documents to Gather Before Applying
Preparation is the best way to keep the financial assessment on track. Lenders typically ask for a standard set of documents, and having them ready can shorten the process by days or weeks. The exact list varies by lender, but most requests fall into a few categories.
- Income verification: Social Security award letters, pension statements, annuity statements, and rental income documentation.
- Asset statements: bank statements, investment account statements, and retirement account statements for the past two to three months.
- Housing expense documentation: property tax bills, homeowners insurance declarations, flood insurance declarations if applicable, and HOA statements.
- Credit and debt information: a recent credit report, credit card statements, and any other loan statements showing monthly obligations.
- Identification and property documents: government-issued ID, proof of ownership, and any trust documents if the home is held in a trust.
Gather these documents before you apply so you can respond quickly to lender requests. If you have income that varies from month to month, be ready to explain the pattern. If you receive help from family members for certain expenses, document that arrangement in writing. Lenders appreciate transparency, and clear documentation can turn a borderline case into an approval.
One more tip: keep your own copy of everything you submit. If a lender asks for the same document twice, you can provide it without delay. And if you decide to compare offers from multiple lenders, you will already have the paperwork ready to go. For broader guidance on mortgage resources and tools, you can explore RefinancingCo's mortgage education resources, which offers calculators and step-by-step guides that complement the reverse mortgage process.
Building a Sustainable Plan After Approval
Approval is not the finish line. A reverse mortgage works best when you have a plan for the years ahead. Review your set-aside balance annually to make sure it is keeping up with actual tax and insurance increases. If you chose to pay property charges yourself, set up a dedicated savings account and automate transfers each month so the money is there when the bills arrive. Keep your servicer informed if you change insurance carriers or if your property tax assessment changes significantly.
It also helps to revisit your budget after closing. A reverse mortgage can eliminate a monthly mortgage payment, but it does not eliminate utilities, food, healthcare, or home maintenance. Build a realistic spending plan that accounts for those costs and leaves room for emergencies. If you find that your residual income is tighter than expected, talk to your servicer about adjusting your set-aside or payment plan before a missed payment becomes a default.
The financial assessment is designed to protect you as much as the lender. It forces a honest look at the numbers and creates a structure for paying the mandatory obligations that keep your home secure. With the right documents, a clear budget, and a willingness to compare offers from multiple lenders, you can move through the process with confidence and secure a reverse mortgage that supports your retirement goals.