Reverse Mortgage Scams and How Seniors Can Avoid Them
Reverse mortgage scams cost seniors millions each year. Learn the red flags and a step-by-step plan to protect your home equity and retirement savings.
By Wesley Lawson
A reverse mortgage can turn home equity into retirement income, but the same features that make it useful also attract fraudsters. Seniors lose millions of dollars each year to reverse mortgage scams, according to the Consumer Financial Protection Bureau and the FBI. The schemes range from outright forgery to slow-burn cons that drain equity over months. Understanding how these scams work is the first step toward keeping your home and your savings safe.
How Reverse Mortgage Scams Target Seniors
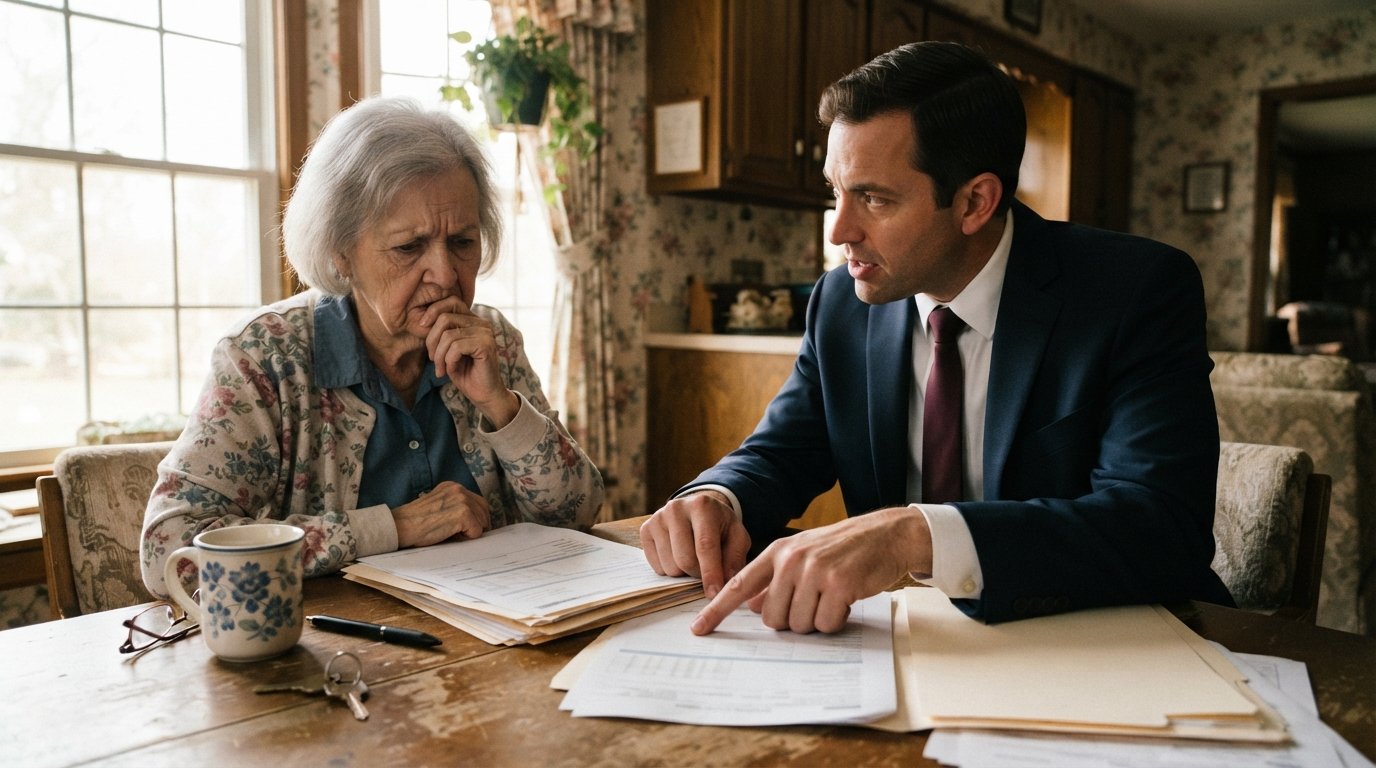
Scammers target reverse mortgage borrowers because the loans involve large lump sums, ongoing lines of credit, and a homeowner who may be less familiar with complex financial products. Many seniors are house-rich and cash-poor, which makes the promise of tax-free cash feel like a lifeline. Fraudsters exploit that pressure with polished mailers, phone calls, and even door-to-door visits.
The typical scam starts with a small request: a signature, a fee, or a referral. It escalates into forged loan documents, stolen equity, or a lost home. In some cases the senior does not realize anything is wrong until a foreclosure notice arrives years later. That delay is exactly what scammers count on.
Reverse mortgage scams often overlap with elder financial abuse. A family member, caregiver, or trusted advisor may use a power of attorney to take out a reverse mortgage without the homeowner's knowledge. Other times the fraud comes from an unlicensed broker or a contractor who promises free home repairs in exchange for a loan. Recognizing the overlap helps seniors and their families watch for warning signs on multiple fronts.
Common Reverse Mortgage Scams to Watch For
Fraudsters reuse a handful of proven playbooks. Knowing them by name makes them easier to spot. Here are the most common reverse mortgage scams reported to regulators and state attorneys general:
- Contractor scams: A contractor offers to arrange a reverse mortgage to pay for repairs, then pockets the money without completing the work.
- Investment schemes: A so-called advisor urges you to take a lump sum from a reverse mortgage and invest it in an annuity, life insurance, or a high-return fund that pays the promoter a commission.
- Forged signatures and powers of attorney: Someone files a reverse mortgage application using your identity or a forged power of attorney, then takes the proceeds.
- Equity theft through deed transfers: A scammer convinces you to add them to the deed or sign over title, then borrows against the home or sells it.
- Fake counseling and origination fees: A caller claims that mandatory HUD counseling costs thousands of dollars upfront, or that a special fee will speed up approval.
Each of these scams has a common thread: someone wants you to move quickly, keep the deal secret, or sign paperwork you have not read. Legitimate reverse mortgage lenders and counselors do the opposite. They encourage questions, provide written disclosures, and never rush a homeowner into a decision.
Red Flags That Signal a Reverse Mortgage Scam
Most reverse mortgage scams share a set of warning signs. A legitimate lender will never pressure you to sign on the spot, never ask you to lie on an application, and never tell you to hide the loan from your family. If you hear any of the following lines, treat the conversation as a potential scam and stop the process immediately.
Be especially cautious when someone promises that a reverse mortgage is "government money" or a "free benefit." A reverse mortgage is a loan that must be repaid when you move out, sell, or pass away. Anyone who describes it as free is either misinformed or trying to mislead you. Similarly, a lender or broker who refuses to put terms in writing, or who asks you to pay large fees in cash or by wire transfer, is almost certainly running a scam.
Step-by-Step: How Seniors Can Avoid Reverse Mortgage Scams
Avoiding reverse mortgage scams is easier when you follow a deliberate process. The steps below are designed to slow the transaction down and put a trusted person in the loop. They also align with the safeguards that legitimate reverse mortgage lenders already follow.
- Get independent HUD-approved counseling first. Reverse mortgage counseling is required for the Home Equity Conversion Mortgage (HECM) program. Use a HUD-approved counselor, not one recommended by the salesperson. The counselor will review costs, alternatives, and your obligations.
- Verify the lender and loan officer. Check licenses with your state's financial regulator and the Nationwide Multistate Licensing System (NMLS). Look up the company's name plus the word "scam" or "complaint" before you sign anything.
- Never sign blank documents or over a power of attorney. Read every page, ask for copies, and refuse to sign anything that has blank fields. If someone insists you are not allowed to keep a copy, walk away.
- Involve a trusted family member or attorney. Bring a son, daughter, or elder-law attorney to every meeting. Scammers rely on isolation, so a witness alone can stop the scheme.
- Report suspicious activity immediately. Contact your state attorney general, the CFPB, or the FBI's elder fraud hotline. Early reporting can freeze a fraudulent loan before funds are disbursed.
Following these steps does not just protect you from scams. It also helps you compare legitimate reverse mortgage offers side by side so you can choose the best terms for your situation. If you are still weighing the pros and cons, our guide on reverse mortgage disadvantages and key risks explains the tradeoffs in plain language.
Understanding Legitimate Reverse Mortgage Protections
The reverse mortgage industry has built-in safeguards that scammers try to bypass. For HECM loans, the Federal Housing Administration requires counseling, limits the amount you can borrow in the first year, and mandates that the lender provide clear disclosures. These rules exist to protect seniors, and any lender who discourages you from using them is a red flag.
Legitimate reverse mortgage lenders also follow strict advertising rules. They cannot claim the loan is government-insured against all losses, cannot promise that you will never lose your home, and cannot use terms like "free money" or "no risk." If a salesperson uses those phrases, ask for the claim in writing and then verify it with a HUD-approved counselor.
Another protection is the non-recourse feature of most reverse mortgages. This means the lender cannot come after your other assets if the loan balance exceeds the home's value. Scammers often ignore or misrepresent this feature, so it is worth confirming in your loan documents. For a broader look at how lending products are explained and compared, the educational resources at LoanFinancing offer plain-language guidance on personal loans and mortgage financing.
What to Do If You Suspect a Reverse Mortgage Scam
If you believe you have been targeted or victimized, act quickly. Contact your bank to flag unusual withdrawals, notify the lender in writing, and file a complaint with the CFPB and your state attorney general. You can also contact the Eldercare Locator at 1-800-677-1116 for local support services.
Keep a written timeline of every conversation, including names, dates, and what was said. This record is valuable if you need to dispute a loan or pursue legal action. If a family member or caregiver is involved, consider contacting Adult Protective Services in your state.
Finally, do not blame yourself. Reverse mortgage scams are designed by professionals who study human psychology. Reporting the scam helps regulators shut down the operation and protects other seniors in your community.
Reverse mortgages can be a legitimate tool for the right homeowner, but only when the process is transparent and unhurried. By getting independent counseling, verifying every professional, and keeping family in the loop, seniors can capture the benefits of a reverse mortgage while shutting out the fraudsters who prey on uncertainty.