Co Borrower vs Cosigner on a Mortgage: Key Differences
Understand what is a co borrower versus cosigner on a mortgage, including ownership, credit impact, and exit strategies to protect your finances.
By Landon Hayes
Co Borrower vs Cosigner: Why the Distinction Matters
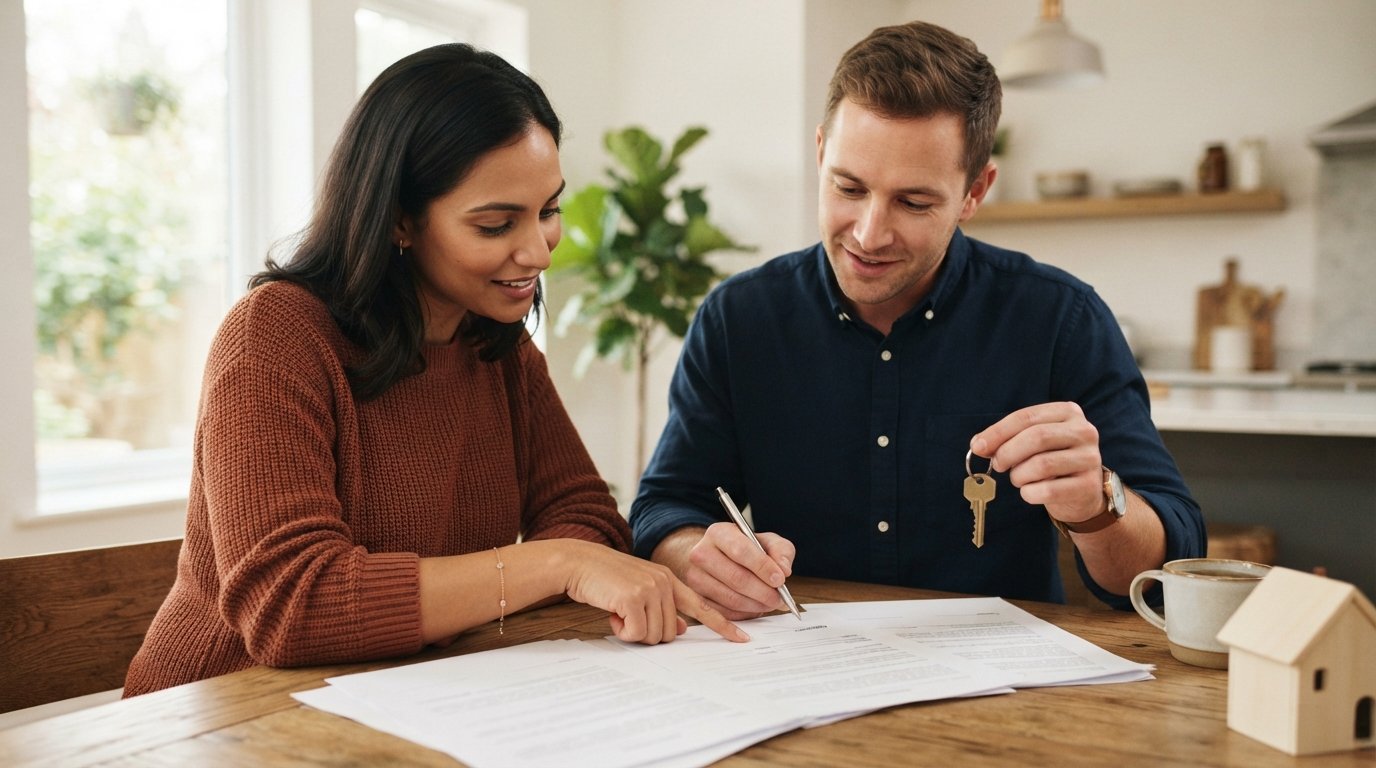
When you need help qualifying for a mortgage, adding another person to the application can seem like a simple solution. But the choice between a co borrower and a cosigner carries major consequences for ownership, liability, and your financial future. Understanding what is a co borrower versus cosigner on a mortgage is essential before you sign any paperwork, because the two roles are not interchangeable. One puts someone on the title and the loan; the other adds a financial backstop without ownership rights. This guide breaks down the differences, the underwriting rules, exit strategies, tax implications, and how to compare quotes when you bring in help.
Defining the Roles: Who Is on Title and Who Is Obligated
The core difference between a co borrower and a cosigner comes down to two things: legal ownership and financial responsibility. A co borrower is typically added to both the mortgage loan and the property title. That means they share ownership of the home and are equally responsible for repaying the debt. A cosigner, by contrast, signs the mortgage note and is obligated to repay the loan if the primary borrower defaults, but they do not appear on the title and have no ownership interest in the property.
This distinction affects everything from credit reporting to your ability to sell or refinance. For example, if you and a co borrower decide to part ways, you may need to refinance or negotiate a buyout because both of you own the home. A cosigner can often be removed through a refinance once the primary borrower qualifies on their own, without transferring ownership. Lenders view these roles differently during underwriting, and the choice influences how your debts are counted, whose credit is scrutinized, and what happens if payments stop.
How Lenders Underwrite Co Borrowers and Cosigners
Mortgage underwriting is the process lenders use to assess risk. When you add a co borrower or cosigner, the lender evaluates that person's credit history, income, assets, and existing debts. However, the way those factors are combined depends on the role. For a co borrower, the lender typically blends both borrowers' incomes and debts into a single debt-to-income (DTI) ratio. Both credit reports are pulled, and the lower score often carries more weight. Because the co borrower is on title, the lender also considers them a co-owner, which can affect occupancy requirements and loan terms.
With a cosigner, the lender usually counts the cosigner's income and credit as a compensating factor, but the primary borrower remains the main focus. Some lenders require the cosigner to have a stronger credit profile than the primary borrower, and the cosigner's debts are still included in the overall DTI calculation. In both cases, the lender wants to see that the combined financial picture supports the loan. For a deeper look at how lenders evaluate borrowers, see our guide on how mortgage lenders evaluate borrowers.
One practical difference: co borrowers are often required to occupy the home as their primary residence, while cosigners may be non-occupant. That makes cosigners more common for investment properties or for parents helping adult children buy a first home. However, not all loan programs allow non-occupant cosigners, so you need to check guidelines for FHA, VA, USDA, and conventional loans before proceeding.
Credit and Debt Consequences for Each Party
Both co borrowers and cosigners share one major consequence: the mortgage appears on their credit report and affects their debt-to-income ratio. Even if the primary borrower makes every payment on time, the co borrower or cosigner may struggle to qualify for other loans because the mortgage debt is counted against them. This is especially important for parents who cosign for a child and later want to refinance their own home or take out a home equity line of credit.
For co borrowers, the impact is more pronounced because they are also on title. Their credit profile is directly tied to the property, and any late payments will damage their score just as much as the primary borrower's. Cosigners face similar credit risk, but they have fewer legal rights to the property. If the primary borrower defaults and the home goes into foreclosure, the cosigner's credit is damaged even though they never owned the home. Before adding anyone to your mortgage, it is wise to review credit reports and discuss worst-case scenarios openly.
Exit Strategies: Removing a Cosigner or Co Borrower
Life changes, and you may eventually want to remove a cosigner or co borrower from the loan. The most common path is to refinance the mortgage in the name of the remaining borrower or borrowers. A refinance pays off the existing loan and creates a new one, so the removed party is no longer obligated. To qualify for a refinance, the remaining borrower must meet the lender's credit, income, and DTI requirements on their own. If the primary borrower's credit has improved since the original purchase, this is often feasible.
For co borrowers, removal also involves transferring ownership. If one co borrower wants to keep the home, they typically need to buy out the other's share or negotiate a quitclaim deed, but a quitclaim alone does not remove them from the mortgage. The lender must approve any change to the loan obligation. Cosigners have no ownership interest, so removing them is strictly a financing matter. In both cases, a refinance is the cleanest solution. Some lenders also offer assumption, where a qualified buyer takes over the existing mortgage, but assumptions are less common and often limited to certain loan types.
If you are considering a refinance to remove a cosigner, compare quotes from multiple lenders to find the best rate and terms. Our guide on mortgage refinance strategies explains how to evaluate offers and avoid common pitfalls.
Tax and Gift Implications of Shared Mortgage Payments
When someone helps you pay the mortgage, the IRS may view those payments as gifts. In 2026, the annual gift tax exclusion allows individuals to give up to $18,000 per recipient without filing a gift tax return (the amount is indexed annually). If a parent pays more than that toward your mortgage, they may need to file a gift tax return, though they likely will not owe tax unless they exceed the lifetime exemption. For co borrowers, shared payments can also create tax complications: if both names are on the title but only one pays, the paying party may be treated as making a gift to the other. Mortgage interest deduction rules also require that you be legally obligated on the loan and itemize deductions to claim the interest.
Cosigners who do not live in the home generally cannot deduct mortgage interest because they are not owners. However, if the cosigner receives rental income or uses the property, different rules apply. It is essential to consult a tax professional to understand your specific situation, especially if large sums change hands or if the home is sold at a gain.
Comparing Quotes When Adding a Co Borrower or Cosigner
Different lenders have different rules for co borrowers and cosigners. Some allow non-occupant cosigners on conventional loans, while others restrict them to certain programs. Credit unions and community banks may be more flexible than large national lenders. When you compare quotes, ask each lender the following questions:
- Does the lender allow cosigners on this loan program? Are there occupancy restrictions?
- How will the co borrower's or cosigner's income and debts be counted in the DTI ratio?
- Will the co borrower or cosigner need to provide full documentation (tax returns, pay stubs, bank statements)?
- What are the requirements to remove the cosigner later through refinancing?
Gathering multiple quotes helps you find the most favorable terms and avoid surprises at closing. MortgageZone's platform connects you with a network of lenders who can provide personalized quotes for your situation, whether you are buying a first home or refinancing. By understanding what is a co borrower versus cosigner on a mortgage, you can make an informed choice that protects both your credit and your relationships.
For a broader perspective on mortgage options and tools, visit RefinancingCo for additional educational resources.
Making the Right Choice for Your Situation
Choosing between a co borrower and a cosigner depends on your goals and the level of involvement you want from the other party. If you want shared ownership and both parties will live in the home, a co borrower arrangement makes sense. If you only need help qualifying and the helper does not want ownership, a cosigner is the better fit. In either case, document your agreement in writing, discuss exit plans upfront, and consult professionals for tax and legal advice. With the right information, you can use these tools to achieve homeownership without unnecessary risk.