First Year of Homeownership Costs Beyond the Mortgage Payment
Budgeting for the first year of homeownership costs beyond the mortgage payment helps you avoid surprise bills and build a realistic emergency fund.
By Wendy Turner
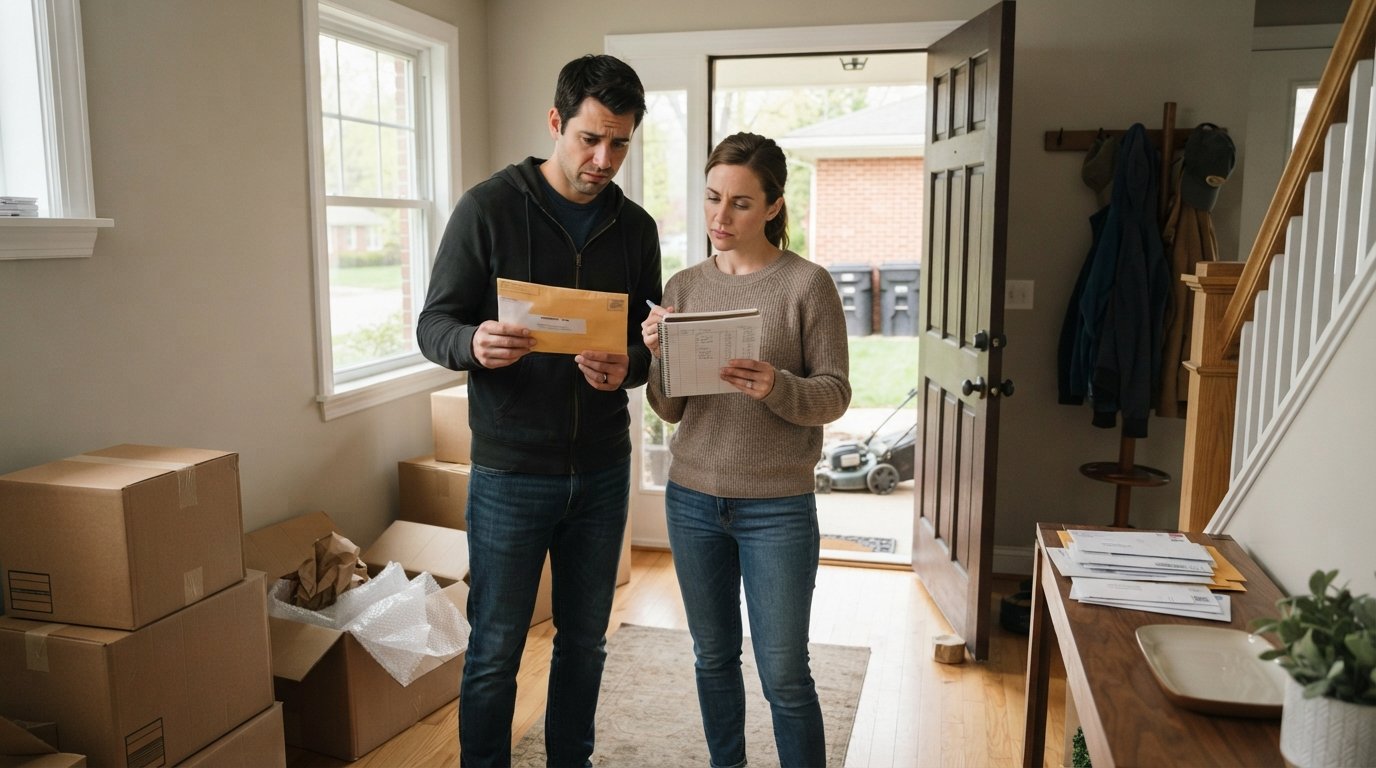
You have saved for the down payment, survived the closing, and finally have the keys. The monthly principal and interest figure on your loan statement feels manageable, and you are ready to settle in. Then the first property tax bill arrives, the water heater fails, and you realize the lawn mower, curtains, and garbage cans were never part of the mortgage calculation. The first year of homeownership costs beyond the mortgage payment routinely surprise new buyers, not because they are hidden, but because they are easy to overlook during the excitement of a purchase.
This guide walks through the real expenses that land in year one, from property taxes and insurance to maintenance reserves and furnishing. It also explains how to build an emergency fund while your equity slowly grows, and when a refinance or home equity option might make sense later. Budgeting for these costs up front turns a stressful first year into a manageable one.
Property Taxes, Insurance, and HOA Dues: The Costs Outside Your Loan Statement
Many buyers assume the number on their preapproval letter covers everything. In reality, property taxes, homeowners insurance, and HOA dues are often paid separately, or they are escrowed into the monthly payment and can change after closing. Property taxes are assessed by local governments and can rise when a home is reassessed at its new purchase price. A buyer who paid $300,000 for a home may see a tax bill based on that value rather than the seller's older assessment, which can add hundreds of dollars per month in some markets.
Homeowners insurance is another line item that deserves attention in year one. Standard policies cover fire, wind, and liability, but in flood zones or wildfire-prone areas, separate coverage may be required. Premiums vary widely by location, home age, and claims history, and a single storm season can push rates higher at renewal. HOA dues add another layer: condos and planned communities often charge monthly or quarterly fees for shared amenities, landscaping, and exterior maintenance. These dues can increase annually and may include special assessments for major repairs, so reading the HOA budget before closing is essential.
To keep these costs predictable, review your closing documents and identify which items are escrowed and which are billed directly. Set up a separate savings bucket for taxes and insurance if you pay them annually, and track HOA increases in your budget. A simple rule is to divide the annual tax and insurance totals by twelve and treat that amount as a fixed monthly expense, even if the bill arrives once or twice a year. For a broader look at how financing choices affect your overall costs, see this guide on how a home financing platform cuts mortgage costs.
Maintenance and Repair Reserves: The 1% Rule and Beyond
Every home requires ongoing maintenance, and the first year often brings a cluster of small repairs that add up quickly. A common guideline is to set aside 1% of the home's purchase price each year for maintenance and repairs. On a $300,000 home, that is $3,000 annually, or $250 per month. Older homes, homes with pools, and properties in harsh climates may need more. The 1% rule is a starting point, not a ceiling.
Year one tends to include both predictable and unpredictable expenses. Predictable items include gutter cleaning, HVAC filter changes, landscaping, and pest control. Unpredictable items include appliance failures, roof leaks, plumbing issues, and electrical problems. A water heater replacement can cost $1,000 to $2,500, while a new roof can run $8,000 or more. Even a modest repair like a garage door spring replacement can cost several hundred dollars.
Here is a practical way to build a maintenance reserve without feeling overwhelmed:
- Open a dedicated savings account labeled home maintenance and automate a monthly transfer based on the 1% rule.
- Schedule a professional home inspection follow-up in the first 30 days to catch issues while any seller warranties are still active.
- Create a seasonal checklist for HVAC, gutters, and exterior caulking so small tasks do not become expensive repairs.
- Keep a digital folder for receipts, warranties, and contractor contacts to simplify future claims and tax records.
After setting up the reserve, review it every quarter. If you have spent less than expected, keep the surplus for future projects. If you have spent more, adjust the monthly transfer upward rather than draining the account. The goal is to avoid using credit cards for routine maintenance, which can turn a small repair into a long-term debt problem.
Utility, Moving, and Furnishing Costs in Year One
Utility costs often jump in the first year because new owners inherit a home with different insulation, appliances, and usage patterns. Electricity, gas, water, sewer, and trash collection can total several hundred dollars per month depending on the region and home size. In some areas, water and sewer bills are billed quarterly and can be surprisingly high if the home has older fixtures or irrigation systems. Budgeting for a 10% to 20% buffer above the previous owner's average usage is a sensible precaution.
Moving costs are another first-year expense that buyers often underestimate. Even a local move can cost $500 to $2,000, while a long-distance move can exceed $5,000. Beyond the truck and movers, there are costs for packing supplies, utility deposits, address changes, and temporary storage. Furnishing a new home is the largest discretionary expense in many first years. Window treatments, rugs, a sofa, a dining table, and basic tools can easily add $3,000 to $10,000, and the temptation to fill every room at once can strain a budget.
A smarter approach is to prioritize needs over wants in the first 90 days. Focus on items that affect safety, sleep, and daily function: a bed, seating, lighting, and basic kitchen supplies. Delay decorative purchases until you have lived in the space and understand how you use it. Track utility usage for the first three months to establish a baseline, then adjust your budget accordingly. If you are still comparing loan options or considering a future refinance, a resource like RefinancingCo can help you understand how rates and terms affect long-term costs.
Building an Emergency Fund While Growing Equity
The first year of homeownership is a balancing act between building an emergency fund and watching your equity grow slowly through principal payments. Equity builds gradually in the early years of a mortgage because most of the monthly payment goes toward interest. An emergency fund, by contrast, provides immediate protection against job loss, medical bills, or major home repairs. Financial planners often recommend three to six months of living expenses in an emergency fund, but new homeowners may need more if their home is older or their income is variable.
To build the fund without neglecting other goals, automate a transfer on payday and treat it like a bill. Start with a $1,000 starter fund, then increase the target as your budget allows. Keep the money in a high-yield savings account so it is accessible but not too easy to spend. Avoid using home equity lines of credit as a substitute for an emergency fund, because tapping equity increases debt and puts your home at risk if you cannot repay.
At the same time, monitor your equity position. After a year of payments, you may have built enough equity to qualify for a refinance or a home equity loan if rates drop or your financial situation changes. Equity also grows if the local market appreciates, though appreciation is never guaranteed. A simple annual review of your loan balance, home value estimate, and emergency fund total can help you decide whether to prioritize debt reduction, savings, or investing.
When a Refinance or Home Equity Option Makes Sense Later
Refinancing or tapping home equity is rarely a first-year priority, but it can become a smart move after you have built a track record of on-time payments and accumulated some equity. A rate-and-term refinance can lower your monthly payment if interest rates have fallen since you closed. A cash-out refinance replaces your mortgage with a larger loan and gives you the difference in cash, which can be used for home improvements, debt consolidation, or other goals. Home equity loans and HELOCs let you borrow against your equity without replacing your first mortgage.
Timing matters. Most lenders want to see at least six to twelve months of payment history before approving a refinance, and some loan programs require a minimum equity stake. Closing costs on a refinance typically run 2% to 5% of the loan amount, so the savings must be large enough to recover those costs within a reasonable period. A break-even analysis, which divides closing costs by monthly savings, helps you decide whether refinancing is worthwhile.
Home equity options also carry risk. Borrowing against your home increases your debt load and reduces the cushion you have if home values decline. Before tapping equity, confirm that you have a stable income, a funded emergency reserve, and a clear plan for repayment. If you are considering a refinance or home equity line, compare offers from multiple lenders and review the total cost of borrowing, not just the interest rate. MortgageZone's comparison tools can help you gather quotes from participating lenders and evaluate your options side by side.
Putting It All Together: A First-Year Budget Framework
A realistic first-year budget includes more than the mortgage payment. Use the following framework to estimate your total housing costs and avoid surprises:
- Add up principal and interest, then add monthly property tax and insurance estimates, plus any HOA dues.
- Set aside 1% of the purchase price annually for maintenance, divided into monthly transfers.
- Estimate utility costs based on the previous owner's history, then add a 10% to 20% buffer.
- Plan for one-time moving and furnishing costs, prioritizing needs over wants in the first 90 days.
- Build an emergency fund with automatic monthly transfers until you reach three to six months of expenses.
After you have these numbers, compare the total to your take-home pay. If the total exceeds 30% to 35% of your gross income, look for ways to reduce discretionary spending or delay optional purchases. A budget that accounts for taxes, insurance, maintenance, and utilities is more accurate than one based on principal and interest alone. It also gives you confidence to handle the unexpected, whether that is a broken appliance or a higher tax assessment.
The first year of homeownership is a learning experience, and costs beyond the mortgage payment are part of the journey. By planning for taxes, insurance, maintenance, utilities, and emergencies, you can protect your investment and enjoy your new home without financial stress. Start with a realistic budget, automate your savings, and revisit your plan every quarter. When you are ready to explore refinancing or home equity options later, MortgageZone can connect you with lenders and tools to compare rates and terms.