How to Buy a House with a Non Married Partner: Mortgage Options
Learn how to buy a house with a non married partner: compare joint mortgage options, title choices, and lender requirements to secure your home.
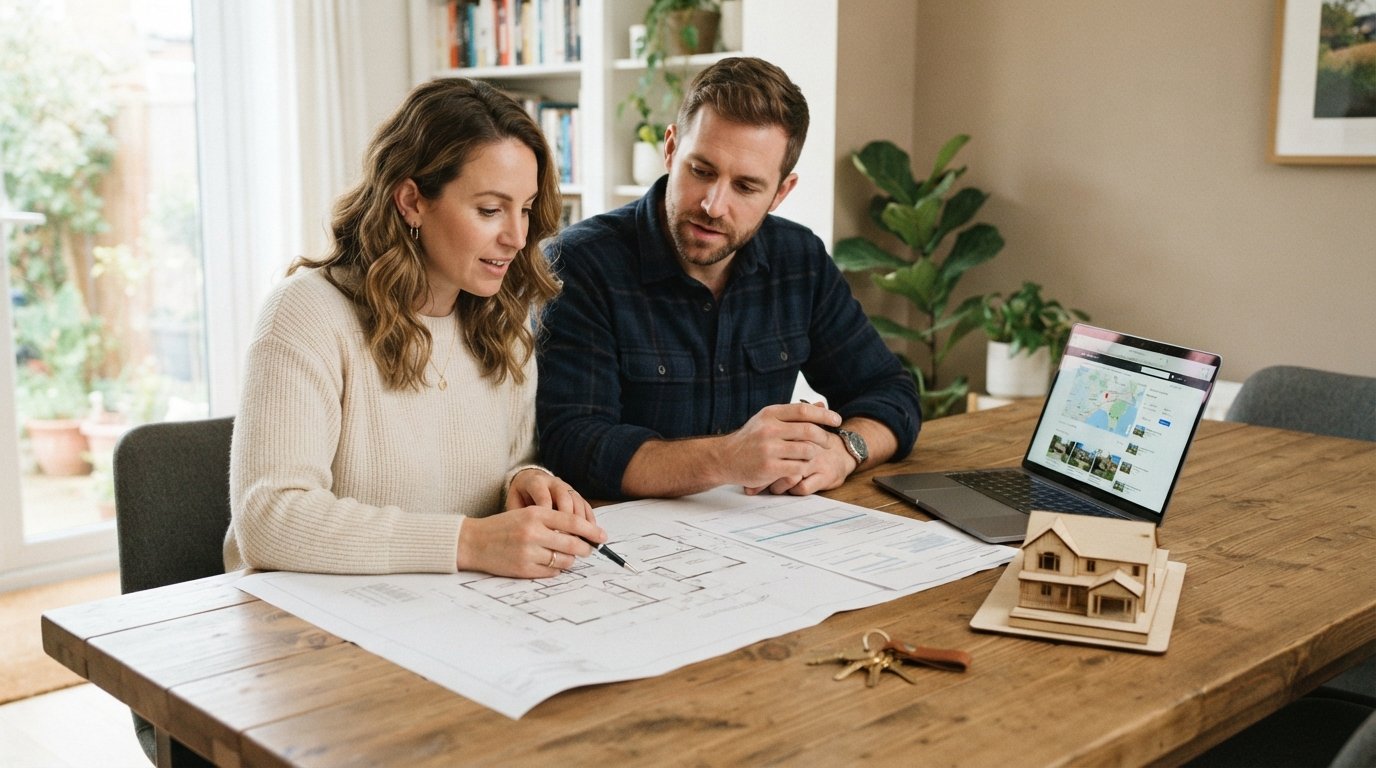
Buying a home with a partner you are not married to is increasingly common, but it comes with financial and legal nuances that married couples often take for granted. Whether you are purchasing with a romantic partner, a friend, or a relative, understanding your mortgage options and how lenders view your application is critical to a smooth transaction. This guide walks you through the key decisions, from choosing the right loan structure to protecting your interests with the proper title and contingency plans.
Joint Mortgage vs. One Borrower on the Loan
When you buy a house with a non married partner, one of the first decisions is whether to apply for a joint mortgage or have only one person on the loan while both go on the title. A joint mortgage means both parties are equally responsible for the debt, and both incomes and debts are considered during underwriting. This can help you qualify for a larger loan amount, but it also means both credit scores and financial histories are scrutinized.
Alternatively, one partner can take out the mortgage alone and both can be on the title. This approach might be necessary if one partner has a significantly lower credit score or high debt-to-income ratio that could jeopardize the application. However, the non borrowing partner will not have their income counted toward qualification, which may reduce the loan amount they can afford. Moreover, the borrowing partner bears sole legal responsibility for the mortgage, while both share ownership. This arrangement requires careful legal planning to ensure fairness.
In our guide on mortgage options for first time buyers, we explain how to navigate similar decisions if you are purchasing your first home. For non married partners, the key is to align your mortgage structure with your ownership goals and risk tolerance.
How Lenders Evaluate Joint Applications
Lenders treat joint mortgage applications by combining the financial profiles of all borrowers. They will review both incomes, debts, credit scores, and assets. The qualifying income is typically the sum of both borrowers' incomes, but debts are also combined. The debt-to-income ratio (DTI) is calculated using the total monthly debts of all borrowers against the total monthly income. This can be advantageous if one partner has a high income but also high debts, as the other partner's lower debt load might balance it out.
Credit scores are another critical factor. Lenders often use the lower of the two middle credit scores when evaluating a joint application. This means if one partner has a poor credit score, it could negatively impact the interest rate offered or even lead to denial. It is wise to review both credit reports and address any issues before applying. MortgageZone's educational resources can help you understand how credit impacts your mortgage options.
Additionally, lenders may require a down payment of at least 3% to 20% depending on the loan program. For joint borrowers, the funds can come from both parties, but lenders will want to document the source of all funds. Gifts from family members are often acceptable but require a gift letter. Understanding these requirements can streamline the preapproval process.
Title Holding: Tenancy in Common vs. Joint Tenancy
How you hold title to the property is a decision that affects what happens if one partner dies or if the relationship ends. The two most common forms of co ownership for unmarried partners are tenancy in common and joint tenancy with right of survivorship.
- Tenancy in Common: Each owner holds a distinct, fractional interest in the property (e.g., 50/50 or 60/40). Interests can be unequal and can be sold or passed to heirs through a will. This is often preferred by unmarried partners who want to control their share separately.
- Joint Tenancy with Right of Survivorship: Owners hold equal shares, and when one dies, their share automatically passes to the surviving owner(s) without probate. This avoids the delay and expense of probate but may not align with the wishes of partners who want to leave their share to family members.
Choosing the right title is not just about death; it also affects how you can sell or transfer your interest. For example, with tenancy in common, you can sell your share without the other owner's consent, though finding a buyer may be difficult. With joint tenancy, both parties must agree to sell. Consulting a real estate attorney is strongly recommended to ensure your title choice matches your intentions.
Contingency Plans for Relationship or Financial Changes
No one wants to think about a breakup or financial hardship, but planning for the unexpected is a hallmark of responsible homeownership. Unmarried partners should have a written agreement that outlines what happens if one party wants to sell, if one can no longer afford the mortgage, or if the relationship ends.
A cohabitation agreement or property agreement can specify how equity will be divided, how decisions about the property will be made, and how disputes will be resolved. It can also address what happens if one partner contributes more to the down payment or mortgage payments. This agreement should be drafted by a lawyer and signed before closing.
Additionally, consider life insurance policies to cover the mortgage in case one partner dies. This can prevent the surviving partner from being forced to sell the home to pay off the loan. Also, establish a plan for maintaining the property and paying bills, such as a joint account for housing expenses. These steps can reduce conflict and protect both parties' investments.
Comparing Mortgage Quotes for Joint Borrowers
When seeking a mortgage as a non married couple, it is essential to compare quotes from multiple lenders. Different lenders have varying criteria for joint applications, and rates can vary significantly based on credit scores, down payment, and loan type. MortgageZone simplifies this process by connecting you with a network of participating lenders who can provide personalized quotes. You can compare offers side by side and choose the one that best fits your financial situation.
Before you start comparing, get preapproved. Preapproval gives you a clear idea of how much you can borrow and strengthens your offer when house hunting. MortgageZone's platform allows you to request quotes quickly and easily, saving you time and potentially money. For those exploring refinancing options later, RefinancingCo offers comprehensive resources and tools to help you navigate the refinance process.
Remember to ask lenders about any specific requirements for joint borrowers, such as whether they allow one borrower to be on the title but not the loan, or how they handle unequal contributions. Being informed empowers you to make the best choice for your partnership.
Frequently Asked Questions
Can we get a mortgage if one partner has bad credit?
Yes, but it may affect the interest rate or require a larger down payment. Some lenders may allow you to exclude the partner with bad credit from the loan, but then their income won't be considered. It's best to discuss options with a lender and consider credit repair strategies.
What if we want to split the down payment unequally?
Lenders typically allow unequal contributions as long as the source of funds is documented. However, you should have a legal agreement that specifies how equity will be divided in the event of a sale or breakup.
How does a non married partner affect taxes?
Unmarried partners cannot file jointly, so each may be able to deduct their share of mortgage interest and property taxes if they itemize. It's advisable to consult a tax professional to understand your specific situation.
Can we add or remove a partner from the mortgage later?
Adding a partner usually requires refinancing and qualifying with the new borrower's income and credit. Removing a partner also typically requires refinancing to release them from the loan obligation. Both processes involve closing costs and lender approval.
Navigating homeownership with a non married partner requires careful planning and clear communication. By understanding your mortgage options, choosing the right title, and preparing for contingencies, you can protect your investment and your relationship. MortgageZone is here to support you with educational resources and connections to lenders who can help you achieve your homeownership goals.