Home Equity vs Balance Transfer: Which Debt Payoff Wins?
Compare using home equity to consolidate debt versus balance transfer offers. Learn which strategy saves more and protects your home.
By Wendy Turner
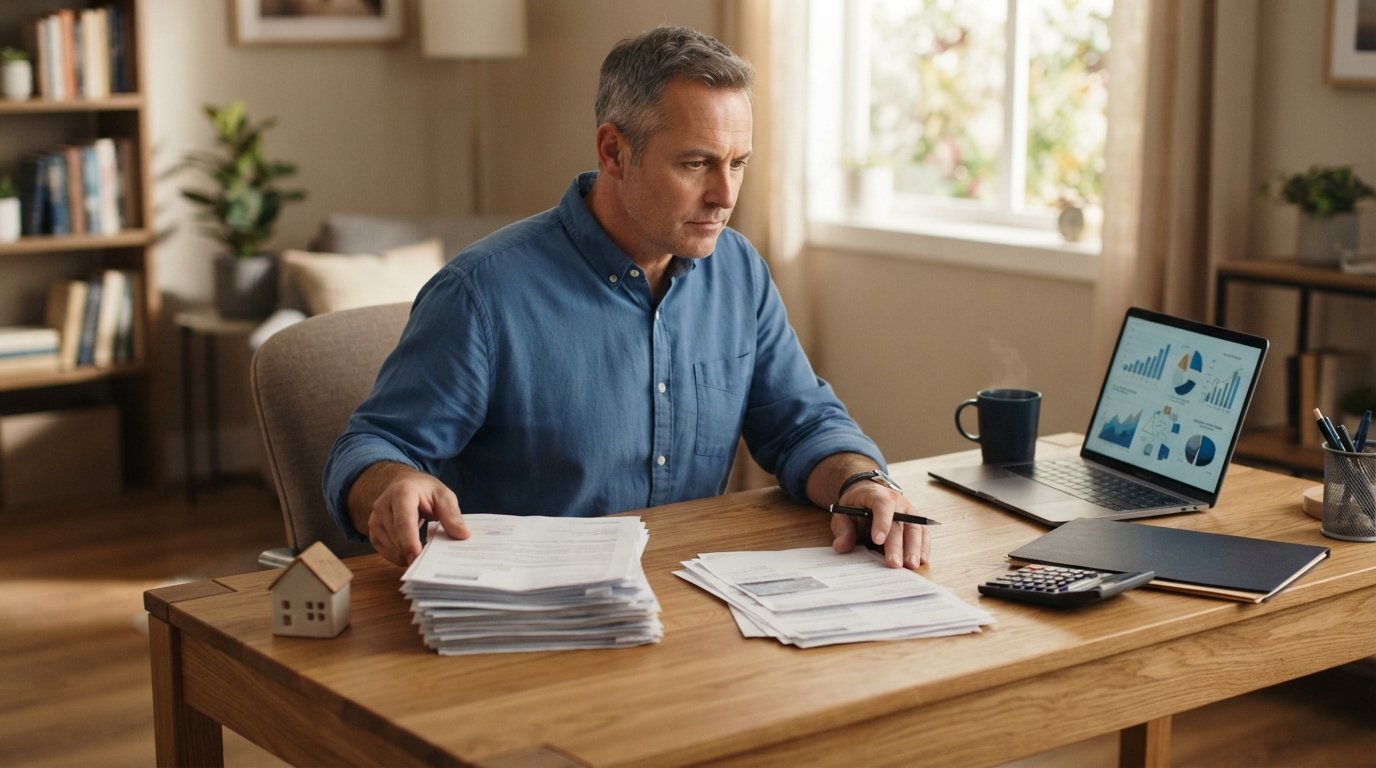
You are staring at a pile of credit card statements and wondering if there is a smarter way to dig out. Two popular strategies often come up: using home equity to consolidate debt versus balance transfer offers that promise zero percent interest for a limited time. Both can reduce the interest you pay, but they carry very different risks, costs, and long-term consequences. Choosing the wrong path could put your home on the line or leave you with a bigger balance when the promotional period ends. This guide breaks down the key differences so you can make an informed decision that fits your financial situation.
How Home Equity Consolidation and Balance Transfers Work
Using home equity to consolidate debt means borrowing against the value of your home, typically through a home equity loan or a home equity line of credit (HELOC). You receive a lump sum or a line of credit and use it to pay off high-interest credit cards, personal loans, or medical bills. The new debt is secured by your house, which usually translates to a lower interest rate than unsecured credit. Repayment terms often range from five to thirty years, giving you a long runway to pay off the balance.
A balance transfer involves moving existing credit card debt to a new card with a low or zero percent introductory APR. Most offers last between 12 and 21 months, after which the rate jumps to a standard purchase APR. You typically pay a balance transfer fee of 3 to 5 percent of the amount moved. The goal is to pay off the balance before the promotional period ends, avoiding the higher rate that follows. Unlike home equity, the debt remains unsecured, so your home is not collateral.
Both options can save you money on interest, but they serve different purposes. Home equity is better for larger balances that need a long repayment horizon, while balance transfers work best for smaller debts you can clear quickly. Understanding these mechanics is the first step in deciding which route aligns with your goals.
Interest Rates and Terms: Home Equity Products vs Credit Cards
Interest rates are often the most visible difference. Home equity loans and HELOCs generally carry fixed or variable rates that are lower than standard credit card APRs. For example, a home equity loan might have a fixed rate in the 7 to 10 percent range, while a credit card might charge 20 percent or more. Over a five-year repayment period, that difference can save you thousands of dollars. However, home equity rates are not guaranteed; they depend on your credit score, loan-to-value ratio, and the lender's terms.
Balance transfer offers advertise zero percent introductory APR, which sounds unbeatable. But these rates are temporary. After the promotional period, the APR can climb to 18 to 25 percent. If you do not pay off the balance in time, the remaining debt becomes expensive. Additionally, the balance transfer fee adds to the cost. On a $10,000 transfer with a 3 percent fee, you pay $300 upfront, which reduces the effective savings.
When comparing terms, consider the length of repayment. Home equity products let you spread payments over many years, which lowers monthly payments but increases total interest paid. Balance transfers require aggressive repayment within a short window to maximize savings. If you can afford to pay off the balance in 12 to 18 months, a balance transfer may be cheaper. If you need more time, a home equity loan could be more cost-effective despite the longer commitment.
The Risk of Converting Unsecured Debt into Secured Debt
One of the most critical differences is the risk profile. Credit card debt is unsecured, meaning it is not tied to any asset. If you fall behind on payments, the worst that can happen is damage to your credit score and potential collection actions. Your home is safe. When you use home equity to consolidate debt, you convert unsecured debt into secured debt. Your house becomes collateral for the new loan. If you default, the lender can foreclose and take your home.
This risk is not theoretical. Life is unpredictable: job loss, medical emergencies, or divorce can disrupt your ability to repay. With a home equity loan, missing payments puts your shelter at risk. Balance transfers do not carry this threat. However, balance transfers have their own risks, such as the temptation to run up new credit card debt after transferring the old balance. If you are not disciplined, you could end up with both the transferred balance and new charges, worsening your financial situation.
Before choosing home equity consolidation, ask yourself if you are comfortable using your home as collateral. If there is any chance you might struggle to make payments, a balance transfer or a debt management plan may be safer. On the other hand, if you have stable income and a solid repayment plan, home equity can be a powerful tool to lower interest costs.
Credit Score Effects: What to Expect from Each Strategy
Both strategies impact your credit score, but in different ways. A balance transfer can temporarily lower your score because opening a new credit card triggers a hard inquiry and reduces the average age of your accounts. However, if you pay down the balance and keep the card open, your credit utilization ratio improves, which can boost your score over time. The key is to avoid closing the old card, as that would shorten your credit history and increase utilization.
Home equity loans and HELOCs also involve a hard inquiry and a new account, which can cause a small dip in your score. But because these are installment loans, they may have a less severe impact on your credit mix compared to revolving credit. On the positive side, consolidating credit card debt with a home equity loan can lower your credit utilization ratio dramatically, especially if you pay off the cards but keep them open with zero balances. That can lead to a score increase within a few months.
One often-overlooked factor is the effect of closing credit cards. If you pay off cards with home equity and then close them, your available credit shrinks, and your utilization ratio may rise. It is usually better to keep the cards open but use them sparingly. With balance transfers, you must also resist the urge to use the old cards, as that can lead to a cycle of debt.
Tax Deductibility: A Key Consideration
Home equity loan interest may be tax-deductible, but only if the funds are used to buy, build, or substantially improve the home that secures the loan. Since 2018, the Tax Cuts and Jobs Act suspended the deduction for interest on home equity debt used for other purposes, such as consolidating credit card debt. So if you use a home equity loan to pay off credit cards, the interest is generally not deductible. There is an exception: if you use the funds to renovate your home, the interest may be deductible up to certain limits.
Balance transfer interest is never tax-deductible because it is consumer debt. However, the zero percent introductory rate means you may not pay any interest during the promotional period, making the tax question moot. If you are considering home equity consolidation, consult a tax advisor to confirm whether your specific use qualifies for the deduction. Do not assume the interest is deductible; many homeowners are surprised to learn it is not.
It is also worth noting that the standard deduction has increased, so many taxpayers do not itemize. If you do not itemize, the deductibility of home equity interest is irrelevant. Run the numbers to see if the potential tax benefit outweighs the risks.
How Much Equity Is Available and How to Calculate It
Before you can use home equity to consolidate debt, you need to know how much you can borrow. Lenders typically allow you to borrow up to 80 to 85 percent of your home's appraised value, minus your outstanding mortgage balance. This is known as the loan-to-value (LTV) ratio. For example, if your home is worth $300,000 and you owe $150,000, you have $150,000 in equity. At an 80 percent LTV, you could borrow up to $240,000 total, meaning you have $90,000 available (since $240,000 minus $150,000 equals $90,000).
To calculate your available equity, follow these steps:
- Get a current appraisal or use an online estimate to determine your home's market value.
- Find your remaining mortgage balance on your latest statement.
- Subtract the mortgage balance from the appraised value to get your total equity.
- Multiply the appraised value by your lender's maximum LTV (e.g., 0.80 for 80 percent).
- Subtract your mortgage balance from that maximum loan amount to find your available equity.
Keep in mind that lenders may have different LTV limits based on your credit score and loan type. A HELOC might allow a higher LTV than a home equity loan. Also, closing costs and fees can reduce the net amount you receive. Always get quotes from multiple lenders to compare offers. MortgageZone can connect you with lenders who offer home equity products tailored to your needs.
When to Choose Home Equity Consolidation
Home equity consolidation makes sense if you have a large amount of high-interest debt and a long repayment horizon. For instance, if you owe $30,000 in credit card debt at 22 percent APR, a home equity loan at 8 percent fixed for 10 years could save you tens of thousands in interest. The monthly payment might be lower than what you are paying now, giving you breathing room. However, you must be confident in your ability to repay over the long term.
This strategy also works well if you need to borrow a significant sum for a home improvement project or a major expense, and you want to consolidate existing debt at the same time. By using a home equity loan or HELOC, you can access funds at a lower rate than personal loans or credit cards. Just remember that the interest may not be deductible if the funds are used for debt consolidation.
Before committing, assess your job stability and emergency savings. If you have a steady income and a cushion, the risk of foreclosure is lower. If not, consider safer alternatives like a balance transfer or credit counseling. For a deeper dive into loan options, see our guide on mortgage refinance vs equity loan.
When a Balance Transfer Is the Better Move
A balance transfer is often the smarter choice if your debt is manageable and you can pay it off within the promotional period. For example, if you have $8,000 in credit card debt and can afford to pay $500 per month, you can clear the balance in 16 months. A 0 percent APR balance transfer with a 3 percent fee would cost you $240, but you would save on interest compared to your current card. This approach keeps your home out of the equation and preserves your equity for emergencies.
Balance transfers also work well if you have a temporary cash flow crunch and need a short reprieve from interest. They can be a lifeline if you are between jobs or facing unexpected expenses. However, you must have a plan to pay off the balance before the promotional period ends. Set up automatic payments and avoid new charges on the card. If you slip up, the standard APR can retroactively apply to the remaining balance in some cases.
Another advantage is that balance transfers do not require an appraisal or closing costs, making them faster and simpler. You can often complete the transfer online in minutes. Just be aware that the transfer fee is typically added to the balance, so you are paying interest on that fee if you do not clear it immediately.
Comparing the Costs: A Side-by-Side Example
Let us compare two scenarios for a homeowner with $20,000 in credit card debt at 20 percent APR. Scenario A: a home equity loan at 9 percent fixed for 10 years. Scenario B: a balance transfer to a card with 0 percent APR for 18 months and a 3 percent fee, followed by a 20 percent APR if not paid off.
- Home equity loan: Monthly payment around $253; total interest paid over 10 years approximately $10,400. Closing costs may apply (2 to 5 percent of the loan amount). Risk: home is collateral.
- Balance transfer: Monthly payment to clear in 18 months around $1,170 (including fee); total interest paid $0 if paid on time. If not paid off, remaining balance at 20 percent APR could cost thousands more. Risk: no collateral, but credit score impact and potential rate hike.
In this example, the balance transfer saves more money if you can afford the higher monthly payment. The home equity loan offers lower monthly payments but costs more in total interest and puts your home at risk. The right choice depends on your cash flow and risk tolerance. If you can commit to aggressive repayment, the balance transfer wins. If you need a longer term and lower payments, home equity may be better.
For personalized quotes on home equity products, visit RefinancingCo to explore your options.
Practical Steps to Decide
To make the best choice, follow a structured approach. First, list all your debts, balances, interest rates, and minimum payments. Calculate how much you can afford to pay each month toward debt. Then, evaluate your job stability and emergency fund. If you have less than three months of expenses saved, adding secured debt may be risky.
Next, get quotes for home equity loans and HELOCs from multiple lenders. Compare APRs, closing costs, and repayment terms. Also, check balance transfer offers from your existing cards or new cards. Read the fine print for fees and promotional periods. Use a spreadsheet to model total costs under each scenario.
Finally, consider your long-term goals. Do you plan to stay in your home for many years? If so, a home equity loan might be less risky because you have time to recover from setbacks. If you plan to move soon, a balance transfer is more flexible. And if you are unsure, consult a nonprofit credit counselor who can review your situation objectively.
Remember that using home equity to consolidate debt versus balance transfer is not a one-size-fits-all decision. It requires honest self-assessment and careful number crunching. By understanding the trade-offs, you can choose the path that leads to financial freedom without jeopardizing your home.