How the Mortgage Preapproval Process Works: A Step-by-Step Guide
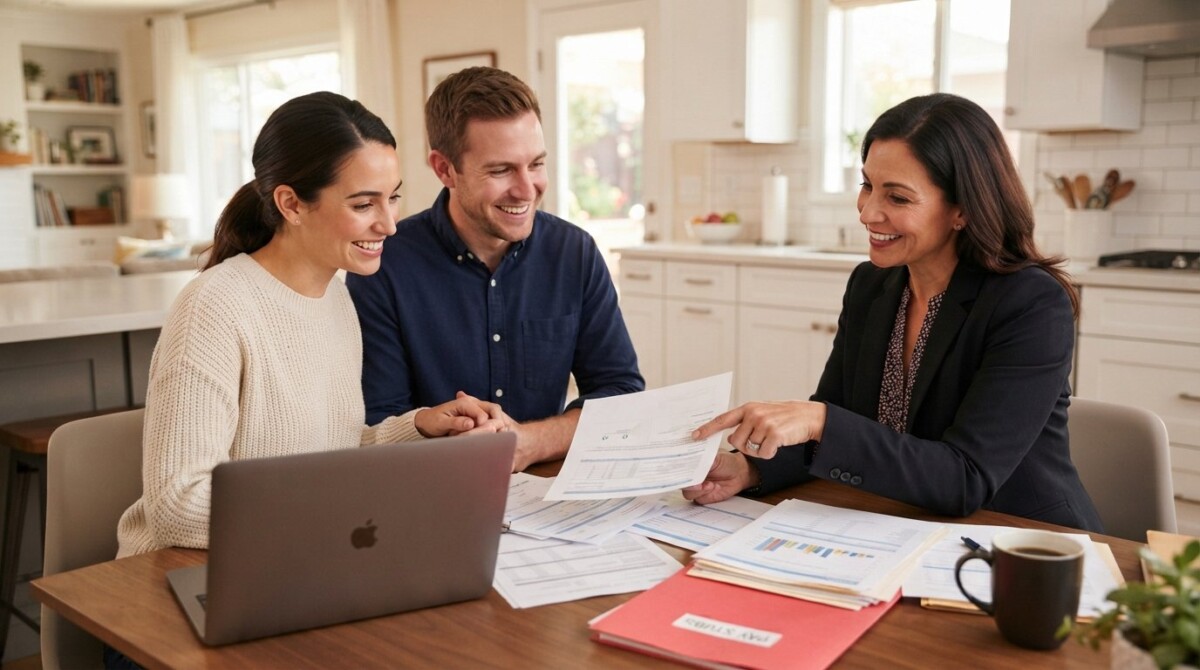
Getting preapproved for a mortgage is often the difference between browsing homes as a window shopper and making a serious offer that sellers respect. Yet many buyers treat preapproval as an afterthought, something to scramble for after they have already fallen in love with a house. Understanding how the mortgage preapproval process works before you start house hunting puts you in a far stronger position. You will know your realistic budget, you will move faster when the right property appears, and you will negotiate from a place of credibility rather than hope. This guide walks through every stage of the process, from the documents you will gather to the moment a lender hands you a preapproval letter, so you can approach your purchase with clarity and confidence.
What Mortgage Preapproval Actually Means
A mortgage preapproval is a conditional commitment from a lender stating how much money they are willing to lend you for a home purchase, based on a preliminary review of your finances. It is not a final loan approval, and it does not lock in an interest rate, but it carries far more weight than a simple prequalification. During prequalification, a lender typically asks a few basic questions about income and debt and gives you a rough estimate. Preapproval goes deeper: the lender verifies your income, pulls your credit report, examines your assets, and runs your numbers through underwriting guidelines before issuing a letter.
That distinction matters because sellers and their agents treat the two very differently. A prequalification letter is a soft signal. A preapproval letter tells the seller that an underwriter has already looked at your file and found it solid enough to lend against, subject to the property appraising and your situation remaining unchanged. In competitive markets, listing agents routinely discard offers that arrive without a preapproval attached.
It helps to think of preapproval as the mortgage world’s version of a background check, one that happens before the deal rather than after. You are proving, with documentation, that the income and assets you claim on your application are real. Once that proof is in hand, the rest of the purchase process, including the final underwriting and closing, tends to move more smoothly because the heavy lifting has already been done.
Why Preapproval Matters Before You Shop
Buyers who skip preapproval often discover their true budget the hard way: after a seller has accepted their offer and the lender’s underwriter starts asking hard questions. By then, you may have paid for inspections and an appraisal, only to learn that the loan amount you assumed was never realistic. Preapproval flips that sequence. It forces the financial review to happen early, when you still have time to adjust your price range, pay down a credit card, or choose a different loan program.
The practical benefits stack up quickly. A preapproval letter:
- Gives you a verified price range so you shop with confidence rather than guesswork
- Signals to sellers and agents that you are a serious, qualified buyer
- Speeds up the offer and negotiation process because your finances are already documented
- Helps you compare loan programs and lenders on real numbers instead of advertised rates
- Reduces the risk of a financing fall-through that could cost you your earnest money
There is also a psychological benefit that buyers rarely anticipate. When you know exactly how much house you can afford, browsing listings becomes focused instead of anxious. You stop touring homes that were never within reach and start evaluating properties you can genuinely pursue. That focus saves weekends, emotional energy, and sometimes thousands of dollars in offers made out of frustration.
One important caveat: a preapproval is not a guarantee. Your financial picture can shift between the letter and the closing, and lenders will re-verify everything before funding the loan. If your income changes, you take on new debt, or you make large unexplained deposits, the preapproval can be revised or revoked. Knowing why mortgage preapproval can change ahead of time helps you protect your approval by keeping your finances stable during the house hunt.
The Step-by-Step Preapproval Process
While every lender has its own workflow, the core sequence of the preapproval process is remarkably consistent across banks, credit unions, and online mortgage marketplaces. Here is how it unfolds, stage by stage.
Step 1: Choose a Lender or Compare Several
Your first decision is who will run your preapproval. You can work with a traditional bank where you already have accounts, a credit union, a mortgage broker who shops multiple wholesale lenders, or an online marketplace that lets you compare quotes side by side. Each option has trade-offs. Banks may offer relationship discounts. Brokers can access niche loan programs. Online comparison platforms tend to surface the widest range of rates quickly, which matters because even a small difference in interest rate translates into tens of thousands of dollars over a 30-year loan.
Because a preapproval requires a hard credit pull, it pays to do your comparison shopping within a short window, typically 14 to 45 days depending on the scoring model. Multiple mortgage inquiries within that window generally count as a single inquiry, so you can gather several preapproval quotes without tanking your credit score.
Step 2: Complete the Application and Submit Documents
Once you have chosen your lender (or lenders), you will fill out a mortgage application, known as the Uniform Residential Loan Application or Form 1003. Expect to provide detailed information about your employment history, income, assets, debts, and the type of property you intend to buy. Then comes the documentation phase, which is where most delays occur. A typical preapproval file includes:
- Recent pay stubs covering the last 30 days
- W-2 forms from the past two years, or tax returns if you are self-employed
- Bank and brokerage statements showing your down payment and reserves
- Government-issued identification and your Social Security number
- Information on any other real estate you own and the associated mortgage payments
Gather these documents before you apply if you can. Lenders can only move as fast as your paperwork allows, and a complete file submitted on day one can shave a week or more off the timeline compared to a file assembled piecemeal.
Step 3: Credit and Financial Review
With your application and documents in hand, the lender pulls your credit report from all three major bureaus and begins verifying the information you provided. They may call your employer to confirm your job, order a written verification of employment, and cross-check your bank statements for large deposits. This stage is essentially a dress rehearsal for the full underwriting that happens after you are under contract.
The lender is calculating two key ratios. Your front-end ratio compares your projected housing payment (principal, interest, taxes, and insurance) to your gross monthly income. Your back-end ratio, also called the debt-to-income ratio, compares all your monthly debt payments, including the new mortgage, to your income. Most conventional loans prefer a back-end ratio at or below 43 percent, though some programs allow higher with compensating factors such as large reserves or a strong credit score.
Step 4: Underwriting and the Preapproval Letter
Once the numbers check out, an underwriter reviews the complete file and issues a decision. If everything is in order, the lender sends you a preapproval letter stating the maximum loan amount, the loan program, and any conditions attached. These conditions might include requirements such as selling your current home first, documenting the source of your down payment, or maintaining a certain credit score until closing.
Read that letter carefully. The loan amount on it is a ceiling, not a target. Many buyers are approved for more than they should comfortably spend once property taxes, insurance, maintenance, and savings goals are factored in. Treat the preapproval number as the outer boundary of your search, and set your personal budget somewhere below it.
How Long Preapproval Takes and What It Costs
In a straightforward situation with clean credit and salaried income, preapproval can take as little as one business day, though two to five days is more typical. Self-employed borrowers, those with complex asset structures, or anyone using gift funds for the down payment should budget extra time, sometimes a week or more, because the lender needs additional documentation and verification.
The good news is that preapproval is usually free. Most lenders do not charge for it because they view it as the first step toward earning your business. Some may charge a small application fee that gets credited toward your closing costs if you ultimately close with them, so ask upfront. What preapproval is not is a rate lock. Rates float until you are under contract and formally lock, which means the rate environment can shift between your preapproval and your closing.
Preapproval letters typically carry a validity window of 60 to 90 days. If your home search stretches beyond that, you will need to refresh the preapproval, which usually involves re-verifying your income, assets, and credit. If anything has changed, the new letter may reflect different terms.
Common Pitfalls That Derail a Preapproval
Even strong borrowers can run into trouble if they make the wrong moves during the preapproval window. The most common mistake is changing jobs, especially moving from salaried work to commission or self-employment, which resets the income verification clock. Lenders want to see stability, and a brand-new employment situation can push your file back to square one.
Another frequent misstep is taking on new debt after preapproval. Financing a car, opening a store card for a furniture purchase, or co-signing a loan for a family member all change your debt-to-income ratio. The lender will re-pull your credit before closing, and a new obligation can shrink your approved amount or kill the loan entirely. If you are unsure whether a financial move could affect your preapproval, explore what changes to mortgage preapproval mean for you before you sign anything.
Large, unexplained deposits are a third landmine. Underwriters must document the source of any significant funds entering your accounts, part of anti-money-laundering requirements. If a relative is helping with your down payment, route the money properly and get a gift letter rather than depositing cash with no paper trail. Keeping your finances boring and transparent during the preapproval window is the surest way to keep your letter intact.
From Preapproval to Closing: What Comes Next
Once you have a preapproval letter in hand, your real estate agent can help you make offers with confidence. When a seller accepts, the file moves into full underwriting, where the lender orders an appraisal, re-verifies your employment and credit, and reviews the property’s title. This is where the preliminary work pays off, because a borrower who was thoroughly vetted at preapproval tends to sail through final approval with fewer surprises. To see how the final stages fit together, our guide on how the mortgage closing process works breaks down the timeline from accepted offer to keys in hand.
Throughout that period, your job is simple: keep your financial life steady. Do not open credit accounts, do not change jobs without telling your lender, and do not move money around without a clear paper trail. Respond to document requests quickly, because every day you save in underwriting is a day closer to your closing date.
The mortgage preapproval process works best when you treat it as the foundation of your home purchase rather than a formality. It tells you what you can afford, shows sellers you are credible, and surfaces financial issues while there is still time to solve them. Start with your documents organized, compare a few lenders on real numbers, and keep your finances quiet until the keys are in your hand. Do those things, and preapproval becomes what it should be: the confident first step toward a home you can genuinely afford.
About Landon Hayes
Recent Posts
Find The Best Rates