Mortgage Application Rejected Reasons: 2026 Lender Checklist
Mortgage application rejected reasons range from low credit to high DTI. Learn the common causes and how to fix them before you reapply.
By Olivia Keller
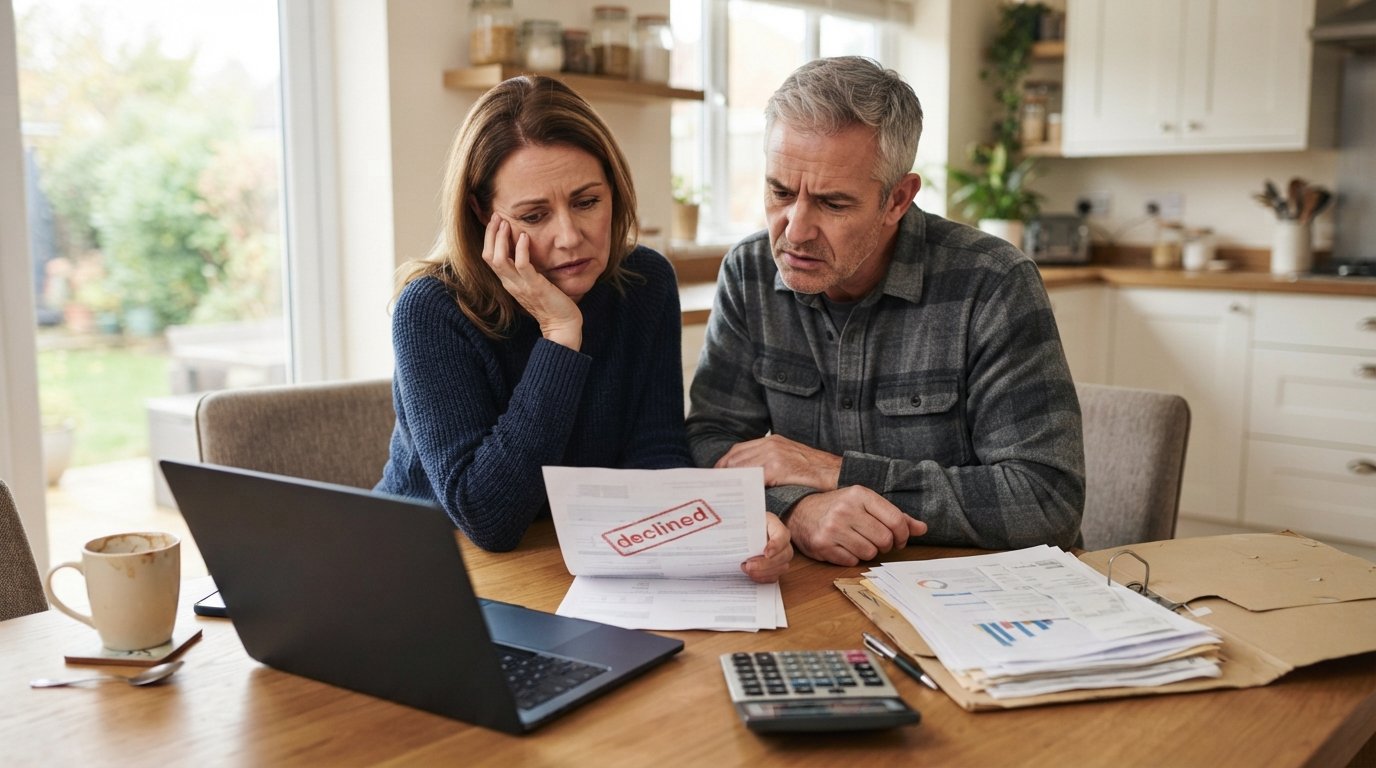
A mortgage rejection can feel like a door slamming shut, but it is rarely the end of the road. Lenders decline applications for specific, fixable reasons, and understanding those reasons is the first step toward a successful second attempt. Whether you are a first-time buyer who just found the perfect home or a homeowner hoping to refinance, knowing why applications fail helps you prepare a stronger file next time. This guide breaks down the most common mortgage application rejected reasons, explains how underwriting decisions are made, and shows you exactly what to do if you receive bad news from a lender.
Why Lenders Reject Mortgage Applications
Mortgage underwriting is a risk assessment process. Lenders want confidence that you will repay the loan on time and in full. They evaluate four core areas: your credit history, your income and employment stability, your existing debt obligations, and the property itself. If any of these areas raises a red flag, the lender may deny the application or require additional documentation before moving forward.
It helps to understand that rejection is not always about a single catastrophic problem. Sometimes it is a combination of smaller issues that together paint a picture of elevated risk. For example, a borrower with a 680 credit score, a recent job change, and a high debt-to-income ratio may be declined even though each factor alone might be manageable. Lenders look at the full picture, and that means you should too.
If you want a deeper dive into the less obvious triggers that cause denials, our guide on why mortgage applications get rejected: 9 hidden causes covers scenarios that many borrowers overlook.
The Most Common Mortgage Application Rejected Reasons
While every lender has its own guidelines, certain rejection reasons appear again and again. Knowing these ahead of time allows you to address problems before you apply, which saves time and protects your credit score from unnecessary hard inquiries.
1. Low Credit Score or Negative Credit History
Your credit score is one of the first things a lender reviews. Most conventional loans require a minimum score of 620, though some programs allow lower scores with compensating factors. FHA loans may accept scores as low as 580 with a 3.5 percent down payment, and VA loans often have more flexible credit requirements. However, a score below the lender's threshold typically results in an automatic denial.
Beyond the score itself, negative items such as late payments, collections, charge-offs, or bankruptcies can sink an application. Lenders look at the entire credit report, not just the number. A recent 30-day late payment on a credit card can be more damaging than an old collection account that has been resolved. If you are unsure where you stand, pull your credit reports from all three major bureaus and review them carefully before applying.
2. High Debt-to-Income Ratio
Your debt-to-income ratio, or DTI, compares your total monthly debt payments to your gross monthly income. Lenders use this figure to determine whether you can comfortably afford a new mortgage payment. Most conventional lenders prefer a DTI below 43 percent, though some allow up to 50 percent with strong compensating factors. FHA loans often permit DTIs up to 57 percent in certain cases.
If your DTI is too high, the lender may deny the application outright or offer a smaller loan amount than you requested. To improve your DTI, you can pay down existing debts, increase your income, or choose a less expensive property. Even reducing a single credit card balance can make a meaningful difference.
3. Insufficient or Unstable Income
Lenders want to see a stable, verifiable income history. If you recently changed jobs, started a new business, or rely on commission or bonus income, the underwriter may question whether your income will continue. Generally, lenders look for at least two years of consistent employment history. Self-employed borrowers often need to provide two years of tax returns and may face additional scrutiny.
Gaps in employment can also raise concerns. If you took an extended leave of absence or were unemployed for several months, be prepared to explain the circumstances and provide documentation showing that you have returned to stable work. In some cases, a strong co-borrower or a larger down payment can offset income concerns.
4. Insufficient Down Payment or Reserves
Many loan programs require a minimum down payment, and some also require cash reserves after closing. For example, conventional loans may require reserves equal to two months of mortgage payments, while investment properties often require six months or more. If you are using gift funds for your down payment, you will need to document the source and provide a gift letter.
Lenders also verify that your down payment funds are seasoned, meaning they have been in your account for at least 60 days. Large, unexplained deposits can trigger questions about whether the money is a loan, which would increase your DTI. Keeping your down payment in a stable account and avoiding unusual deposits during the application process helps prevent delays or denials.
5. Property Appraisal Issues
The property itself can be a reason for rejection. If the appraisal comes in lower than the purchase price, the lender may reduce the loan amount, requiring you to bring more cash to closing. In some cases, the lender may deny the loan if the appraisal reveals significant condition issues, such as a failing roof, foundation problems, or safety hazards.
Appraisal gaps are common in competitive markets where buyers bid above asking price. If you are concerned about an appraisal shortfall, consider including an appraisal contingency in your purchase contract or negotiating with the seller to cover the difference.
Here is a quick summary of the most frequent rejection triggers:
- Credit score below the lender's minimum or recent negative credit events
- Debt-to-income ratio exceeding program limits
- Unstable employment or inability to document income
- Insufficient down payment, closing costs, or cash reserves
- Appraisal below purchase price or property condition problems
Each of these issues can be addressed with planning. The key is to identify weaknesses in your profile before you apply, not after.
Less Obvious Reasons Mortgage Applications Get Denied
Some rejection reasons are not immediately obvious, even to borrowers with strong credit and stable income. These hidden causes often catch applicants by surprise and can be frustrating because they seem unrelated to affordability.
Recent Large Purchases or New Credit Accounts
If you finance a new car, open a new credit card, or make a large purchase on credit during the mortgage process, you can inadvertently change your DTI and credit profile. Lenders often re-pull credit just before closing, and new debt can push your ratios over the limit. Avoid major financial changes between application and closing.
Errors on the Credit Report
Credit reporting errors are more common than many people realize. An account that is not yours, a payment reported late when it was on time, or a collection that should have aged off can all lower your score and trigger a denial. Reviewing your reports early gives you time to dispute inaccuracies and correct the record.
Undisclosed Liabilities
If you co-signed a loan for a family member or have other undisclosed obligations, those debts count against your DTI. Lenders will find them during underwriting, and failing to disclose them can damage your credibility. Always provide complete information about your financial obligations.
Changing Jobs During the Process
Even a promotion can complicate your application if it changes how you are paid. Switching from salaried to commission-based pay, for example, may require additional documentation and could delay or derail the loan. If you are considering a job change, discuss it with your loan officer first.
Insufficient Documentation
Missing paperwork is a surprisingly common reason for delays and denials. Lenders need proof of income, assets, identity, and other details. If you cannot provide the required documents in a timely manner, the underwriter may suspend or deny the application. Staying organized and responsive throughout the process helps avoid this outcome.
What to Do If Your Mortgage Application Is Rejected
Receiving a denial is discouraging, but it is not permanent. The first step is to ask the lender for a specific reason in writing. Under the Equal Credit Opportunity Act, you are entitled to an adverse action notice explaining why your application was denied. That notice will tell you which factor or factors led to the decision.
Once you understand the reason, you can take targeted action. If credit is the issue, work on improving your score by paying down balances, disputing errors, and avoiding new credit inquiries. If DTI is the problem, focus on reducing debt or increasing income. If the property did not appraise, you may need to renegotiate the price or find a different home.
Consider working with a mortgage broker or loan officer who can review your situation and recommend programs that fit your profile. Some lenders specialize in borrowers with past credit challenges, and government-backed loans like FHA, VA, and USDA often have more flexible guidelines than conventional loans.
It also helps to compare offers from multiple lenders. Different lenders have different risk appetites and underwriting overlays. A loan that one bank denies might be approved by another. Using a platform like Express Mortgage Quotes can help you gather quotes from multiple lenders and see which ones are more likely to work with your situation.
How to Strengthen Your Next Mortgage Application
Preparation is the best defense against rejection. Before you apply again, take these steps to present the strongest possible file:
- Review your credit reports and dispute any errors. Aim for a score that meets or exceeds the lender's minimum.
- Lower your DTI by paying down credit cards, personal loans, and other debts. Even small reductions can help.
- Document your income thoroughly. Gather pay stubs, W-2s, tax returns, and proof of any additional income sources.
- Save for a larger down payment and build cash reserves. A bigger cushion reduces risk in the lender's eyes.
- Avoid major financial changes during the process. Do not change jobs, finance a car, or open new credit accounts until after closing.
Following these steps does not guarantee approval, but it significantly improves your chances. Lenders want to say yes, and a well-prepared application makes their decision easier.
It is also wise to get preapproved before you start house hunting. A preapproval letter shows sellers that you are a serious buyer and gives you a clearer picture of what you can afford. If you are denied for preapproval, you have time to address the issues before you are emotionally invested in a particular property.
Final Thoughts on Mortgage Rejection
A mortgage denial is a setback, not a verdict on your financial future. The reasons behind rejections are almost always fixable with time, effort, and the right guidance. By understanding the common causes, from credit issues to DTI problems to appraisal gaps, you can take control of the process and position yourself for success.
Start by reviewing your credit and finances early. Gather your documents, reduce your debt, and consider speaking with a loan officer who can help you navigate the options. Whether you are buying your first home, refinancing, or exploring a reverse mortgage, the key is to be proactive and informed. With the right preparation, your next mortgage application can have a very different outcome.