Seller Paid Closing Costs vs Lower Price: Which Is Better?
Seller paid closing costs vs lower purchase price which is better? Compare long-term savings and cash needs to choose the right negotiation strategy.
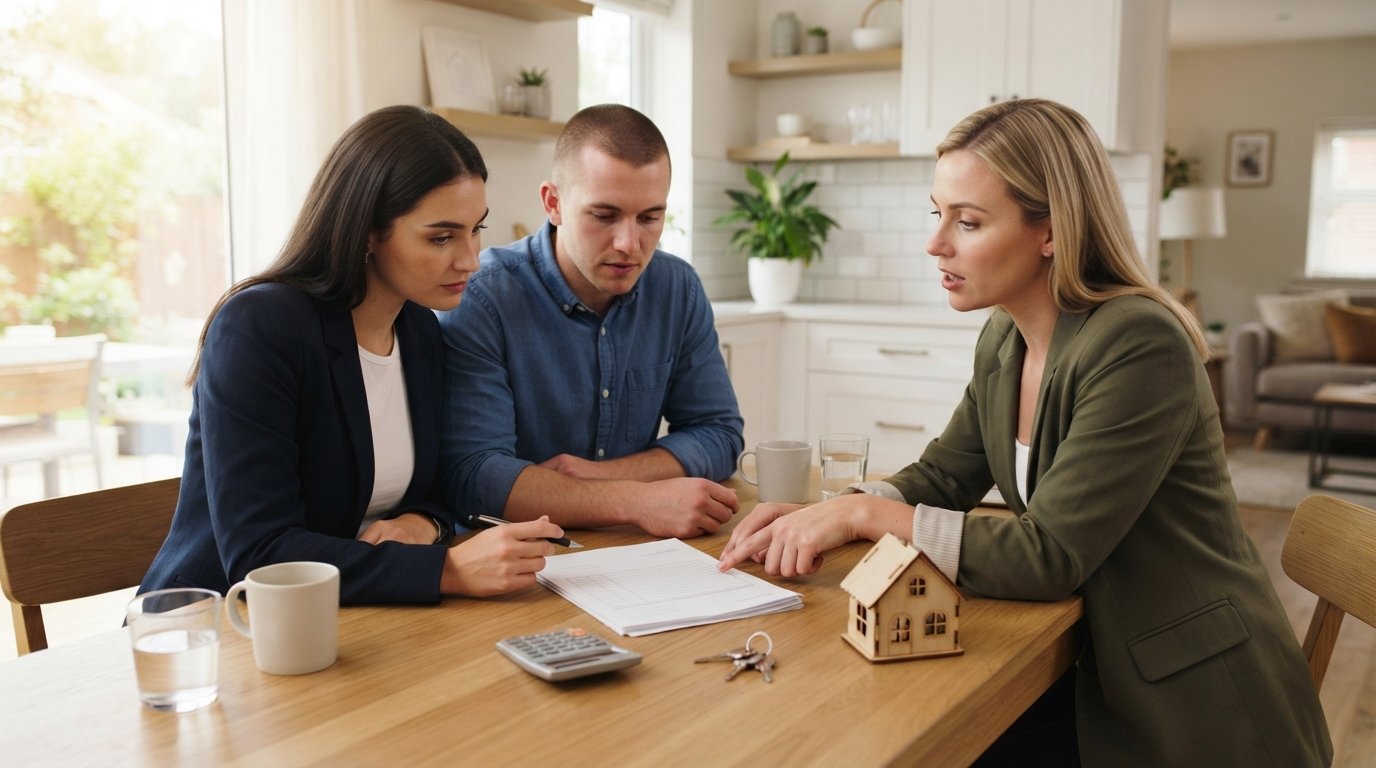
You have found the house. The inspection is done. Now comes the part where every dollar counts: negotiating the final terms. Your agent asks whether you want to ask the seller to cover some of your closing costs or simply reduce the purchase price. On the surface, both seem like a win, but they affect your wallet in very different ways. Choosing between seller paid closing costs and a lower purchase price is not just a math problem; it is a strategic decision that depends on your cash position, your loan type, and your long-term plans for the home.
This guide breaks down the real-world impact of each option so you can walk into negotiations with clarity. We will look at how loan limits cap concessions, why a lower price can save you money for years, and when taking cash upfront is the smarter move. We will also show you how to structure an offer that survives the appraisal, and where to find tools to compare mortgage options before you commit. By the end, you will know exactly which lever to pull for your situation.
Understanding Seller Concessions and Price Reductions
Seller concessions, often called seller paid closing costs, are credits the seller agrees to pay on your behalf at closing. These funds cover items like loan origination fees, title insurance, appraisal costs, and prepaid interest. The key point is that the money does not come out of your pocket at closing; it is baked into the transaction. However, lenders limit how much the seller can contribute, and those limits vary by loan program and down payment size.
A lower purchase price, by contrast, reduces the total amount you borrow. If the home is listed at $400,000 and you negotiate a $390,000 price, your loan amount drops. That smaller loan means lower monthly principal and interest, and it also affects your loan-to-value ratio, which can influence mortgage insurance and future refinancing options. Unlike concessions, a price reduction is not capped by loan guidelines.
Both strategies have a place, but they serve different goals. Concessions help you preserve cash at closing, while a price cut builds equity and reduces long-term costs. The right choice hinges on your financial reserves and how long you plan to stay in the home.
How Loan Type Caps Seller Concessions
Before you ask for a credit, you need to know the ceiling. Conventional loans, FHA loans, VA loans, and USDA loans each have their own rules. These caps are based on the lesser of the purchase price or the appraised value, and they are expressed as a percentage of the loan amount.
- Conventional loans: The cap ranges from 3% to 9% depending on your down payment. A 3% down payment limits concessions to 3%, while a 25% down payment allows up to 9%.
- FHA loans: Seller concessions are capped at 6% of the purchase price. This is generous compared to conventional limits, but it is still a hard ceiling.
- VA loans: The VA allows sellers to pay all closing costs, up to 4% in concessions for certain items. However, you cannot use concessions to reduce the down payment.
- USDA loans: Seller contributions are limited to 6% of the sales price.
These caps matter because they restrict how much you can ask for. If your closing costs exceed the limit, you will need to cover the difference. A lower purchase price, on the other hand, has no such cap. You can negotiate the price down as far as the seller will accept. That flexibility is why some buyers prefer a price reduction when closing costs are modest.
Understanding these limits is the first step in comparing seller paid closing costs vs lower purchase price. If your loan program allows a generous concession, you might be able to cover most of your closing costs. If not, a price cut may be the only way to achieve your target monthly payment.
The Long-Term Impact of a Lower Purchase Price
A lower purchase price does more than reduce your monthly mortgage payment. It also lowers your property taxes in many jurisdictions, because property taxes are often based on the assessed value, which is tied to the purchase price. Over several years, that difference can add up to thousands of dollars saved. Similarly, homeowners insurance premiums are partly based on the home's replacement cost, which is influenced by the purchase price. A lower price can lead to lower insurance premiums.
Future equity is another factor. When you buy at a lower price, you start with a smaller loan balance. As you pay down the mortgage and the home appreciates, your equity grows faster. If you plan to refinance or sell in a few years, a lower starting price can give you more room to maneuver. For example, if you buy at $390,000 instead of $400,000, your loan-to-value ratio is lower from day one. That can help you avoid private mortgage insurance sooner or qualify for better refinance terms.
However, a lower price might not always be achievable. Sellers may resist reducing the price if they need a certain amount to pay off their own mortgage or if they believe the home is worth more. In a competitive market, they might favor offers with a higher price and concessions over a lower price. That is why it is important to weigh the trade-offs carefully.
When Seller Concessions Make Sense
Seller concessions are most valuable when you are cash-tight. If you have just enough for a down payment but little left for closing costs, a credit from the seller can help you close the deal without draining your savings. This is especially common for first-time homebuyers who are stretching to afford the down payment. By asking the seller to cover some or all of your closing costs, you can keep more cash in reserve for moving expenses, immediate repairs, or an emergency fund.
Concessions also help when you want to preserve liquidity for other investments or expenses. For example, if you are buying a home and also planning a major renovation, you might prefer to keep your cash available rather than tie it up in closing costs. In that case, a concession is a way to finance your closing costs through the seller, effectively rolling them into the purchase price. You will pay interest on that amount over the life of the loan, but the monthly impact may be minimal.
Another scenario where concessions shine is when you are up against loan limits. If you are using an FHA loan and your closing costs are high, a 6% concession can cover a significant portion. That can make the difference between closing comfortably and scraping together every last dollar. Just remember that concessions increase your loan amount, which means you will pay interest on them. But if you plan to stay in the home for a long time, the extra interest may be a small price to pay for the cash flow relief.
When a Lower Purchase Price Wins
If you have adequate cash reserves, a lower purchase price often delivers better long-term value. You will pay less interest over the life of the loan because the principal is smaller. You will also build equity faster and may qualify for lower insurance premiums. Over 30 years, the savings can be substantial. For example, on a $400,000 loan at 6% interest, reducing the price by $10,000 saves you about $60 per month in principal and interest, which adds up to more than $21,000 over the life of the loan.
A lower price also gives you more flexibility if home values decline. If you buy at a lower price, you have a cushion against negative equity. That is a key consideration in uncertain markets. Additionally, a lower price can help you avoid jumbo loan limits or stay within conforming loan limits, which can offer better interest rates.
Buyers with reserves should also consider that a lower price reduces the amount they need to bring to closing. While closing costs remain the same, the overall cash needed is lower because the down payment is based on a smaller purchase price. That can free up cash for other goals, such as investing or saving for future needs.
How to Structure the Offer So the Credit Survives Appraisal
One of the biggest risks with seller concessions is that the appraisal might come in lower than the purchase price. If that happens, the lender may reduce the loan amount, and the concession could be lost. To protect your credit, you need to structure the offer carefully. Here is a step-by-step approach:
- Get preapproved first. Know your loan limits and how much you can afford. This helps you set realistic expectations for concessions.
- Ask for a specific dollar amount, not a percentage. This makes it clear what you need and avoids confusion if the price changes.
- Include an appraisal contingency. If the appraisal comes in low, you can renegotiate the price or the concession amount without losing your earnest money.
- Consider a higher purchase price with a concession. Sometimes sellers prefer a higher price with a credit because it makes their home appear more valuable. But be careful: a higher price can lead to a higher appraisal, which may not support the concession.
- Work with a knowledgeable agent. They can guide you on local market norms and help you draft an offer that protects your interests.
Another strategy is to ask for a credit that is applied to specific closing costs rather than a general credit. For example, you might ask the seller to pay for the title insurance and appraisal, which are required by the lender. This can be more palatable to sellers and may survive appraisal issues better than a blanket credit.
If you are unsure how to compare mortgage offers with different concession structures, you can use online resources to run the numbers. For a deeper dive into the individual fees that make up closing costs, see our guide on mortgage closing costs explained. It breaks down each line item so you know exactly what you are asking the seller to cover.
Comparing the Numbers: A Side-by-Side Example
Let us look at a hypothetical scenario to illustrate the difference. Suppose you are buying a $400,000 home with a 30-year fixed-rate mortgage at 6% interest. You have $20,000 for a down payment (5%) and your closing costs are estimated at $12,000. You have two options: ask the seller for a $12,000 concession or negotiate the price down to $388,000.
With the concession, your loan amount is $380,000 (after 5% down on $400,000). You pay no closing costs out of pocket, but you finance the $12,000 over 30 years. Your monthly principal and interest payment is about $2,278. Over the life of the loan, you will pay roughly $440,000 in principal and interest, including the concession amount.
With the lower price, your loan amount is $368,600 (after 5% down on $388,000). You pay $12,000 in closing costs out of pocket. Your monthly principal and interest payment is about $2,210. Over 30 years, you pay about $427,000 in principal and interest. That is a savings of about $13,000 compared to the concession option. However, you needed $12,000 cash upfront.
Which is better? If you have the cash, the lower price saves you money. If you do not have the cash, the concession gets you into the home with less out of pocket. The decision comes down to your financial situation and your priorities.
Factors to Consider Beyond the Numbers
While the math is important, other factors can influence your choice. Consider your plans for the home. If you intend to sell in a few years, a lower purchase price can help you build equity faster, which means more profit when you sell. If you plan to stay for decades, the monthly savings from a lower price will compound over time.
Also think about your tax situation. Mortgage interest is often tax-deductible, but a lower loan amount means less interest to deduct. However, the standard deduction may be higher than your itemized deductions, so the tax benefit of a larger mortgage might be minimal. Consult a tax advisor for personalized advice.
Another factor is the seller's motivation. If the seller is eager to close, they may be more willing to offer concessions. If they are holding out for a higher price, a price reduction might be harder to negotiate. Understanding the seller's position can help you craft an offer that meets your needs and theirs.
Finally, consider the market. In a buyer's market, you may have more leverage to negotiate either concessions or a lower price. In a seller's market, you might need to choose the option that makes your offer more attractive. A concession can be appealing to sellers because it does not lower the list price, which can affect future appraisals and comps. However, some sellers prefer a straightforward price reduction.
Making the Decision: A Simple Framework
To decide between seller paid closing costs and a lower purchase price, ask yourself these questions:
- Do I have enough cash to cover closing costs without draining my reserves?
- How long do I plan to stay in the home?
- What is my loan type and what are the concession limits?
- Is the seller more likely to agree to a concession or a price reduction?
- How important is a lower monthly payment versus lower upfront cash?
If you have ample cash and plan to stay long-term, a lower purchase price is usually the better financial move. If you are cash-tight or plan to move sooner, a concession can provide the flexibility you need. There is no one-size-fits-all answer, but understanding the trade-offs empowers you to make an informed choice.
For additional tools and resources to compare mortgage options, consider exploring RefinancingCo, which offers calculators and guides to help you navigate the home loan process. Whether you are buying or refinancing, having a clear picture of your options is essential.
In the end, the best strategy is the one that aligns with your financial goals and risk tolerance. Negotiate with confidence, knowing that you have weighed both sides of the seller paid closing costs vs lower purchase price debate. With careful planning, you can secure the home you want on terms that work for you.