Mortgage Contingency in a Purchase Contract: Buyer Guide
A mortgage contingency in a purchase contract protects your earnest money if financing falls through. Learn deadlines, waiver risks, and appraisal rules.
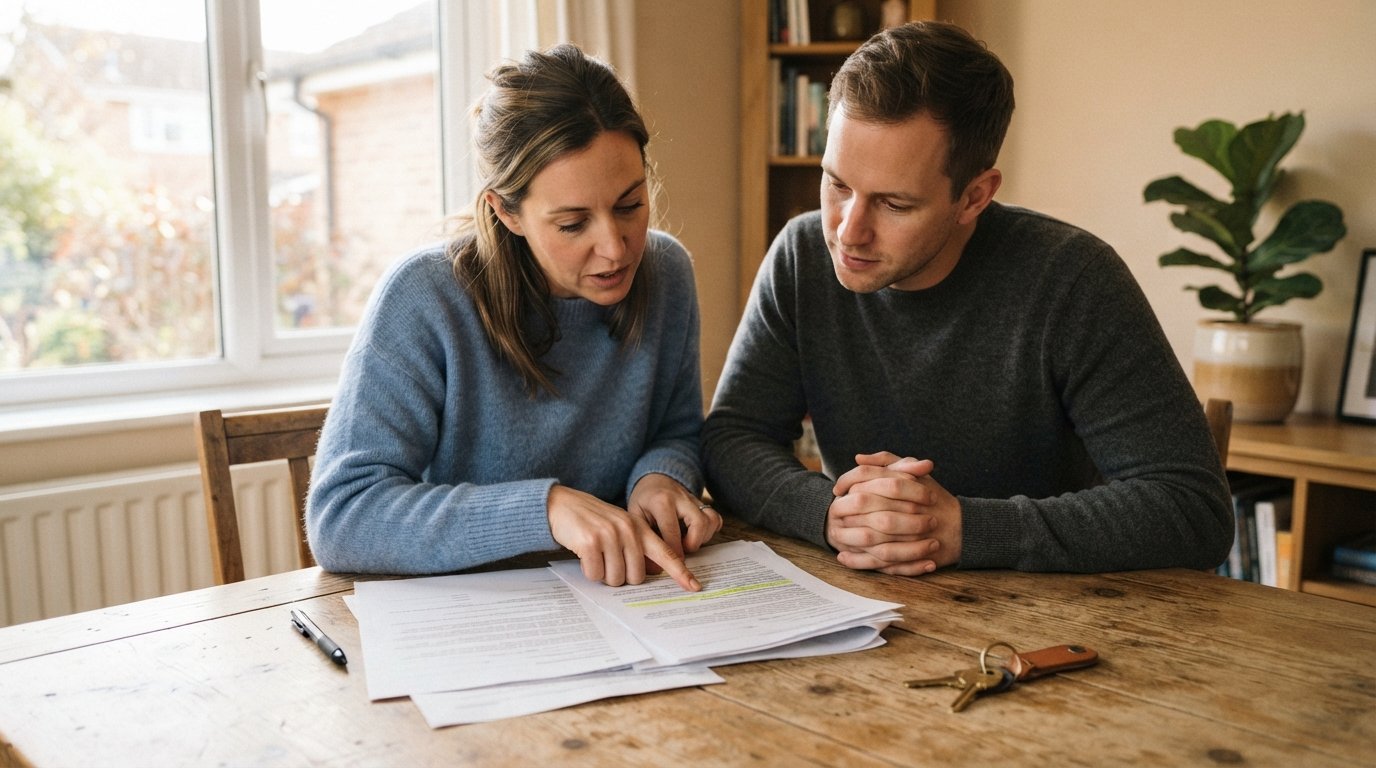
You found the house, negotiated a price, and signed the purchase agreement. Then the unthinkable happens: your financing falls through. Without the right clause in your contract, you could lose your earnest money deposit and the home itself. That safety net is exactly what a mortgage contingency provides, and understanding how it works is essential before you sign on the dotted line.
What a Mortgage Contingency Clause Actually Commits Buyer and Seller To
A mortgage contingency, sometimes called a financing contingency, is a contractual provision that makes the sale of the home conditional on the buyer securing a mortgage loan. When you ask what is a mortgage contingency in a purchase contract, the short answer is this: it is a protective clause that lets you walk away with your deposit if you cannot obtain financing under the terms spelled out in the agreement. The clause typically specifies the loan amount, the maximum interest rate, the loan type (such as a fixed-rate or adjustable-rate mortgage), and the deadline by which financing must be secured.
The seller agrees to take the property off the market and wait while the buyer completes the loan application and underwriting process. In exchange, the buyer commits to applying for financing promptly and in good faith. Neither party is making a casual promise: the buyer must actively pursue a loan that matches the terms in the contract, and the seller must refrain from accepting backup offers during the contingency period, assuming the contract provides for that exclusivity.
If the buyer fails to secure financing by the deadline and the contingency is still in force, the buyer can typically terminate the contract and recover the earnest money deposit. If the buyer secures financing, the contingency is satisfied and the sale proceeds toward closing. The clause therefore functions as a risk allocation tool: it shifts the danger of loan denial away from the buyer's deposit and onto the shoulders of the transaction itself.
It helps to think of the financing contingency as a checklist of commitments on both sides. Here is what each party is generally agreeing to:
- Buyer commitments: Submit a complete loan application promptly, provide accurate financial documentation, cooperate with the lender's underwriting requests, and pursue a loan that meets the contract's stated terms.
- Seller commitments: Keep the property available during the contingency period, maintain the home in its current condition, and cooperate with appraisal and inspection access.
- Shared obligations: Meet the financing deadline, communicate promptly about any issues, and follow the contract's procedures for extending or terminating the agreement.
Because the exact language varies by state and by the standard purchase contract form used in your market, it is worth reading the clause carefully with your real estate agent or attorney. A well-drafted contingency protects you, but a vague or shortened one can leave you exposed.
Typical Timelines and What Happens if Financing Falls Through
Financing contingencies usually run between 21 and 45 days, though the exact window depends on the market, the loan type, and the complexity of your financial situation. Conventional loans often close within 30 days, while FHA, VA, and USDA loans may need slightly longer because of additional appraisal and eligibility requirements. In a fast-moving market, sellers may push for shorter contingency periods, sometimes as short as 14 days, which puts pressure on buyers to have their documentation ready in advance.
If financing falls through, the process depends on why it failed and whether the failure is covered by the contingency. A lender denial based on the buyer's credit, income, or debt-to-income ratio is generally covered. A denial caused by an appraisal that comes in below the purchase price may be covered by a separate appraisal contingency, which is why buyers should understand how the two clauses interact. If the buyer simply fails to apply on time or refuses to provide documents, the seller may argue the buyer did not act in good faith and may attempt to keep the deposit.
The sequence below shows how a typical financing contingency plays out from contract signing to resolution:
- Contract execution: Both parties sign the purchase agreement, and the buyer delivers the earnest money deposit to escrow.
- Loan application: The buyer submits a full application to the lender, ideally within the first few days after signing.
- Underwriting and appraisal: The lender reviews income, assets, credit, and the property appraisal, often issuing conditional approval before final clearance.
- Deadline review: Before the contingency deadline, the buyer and agent confirm whether financing is approved or whether an extension is needed.
- Resolution: If financing is approved, the contingency is removed and the sale moves to closing. If financing is denied and the contingency applies, the buyer terminates and recovers the deposit.
Communication during this window matters enormously. If your lender flags a problem, tell your agent immediately so the seller can be notified and an extension requested if needed. Sellers are often more willing to grant a short extension when they see a legitimate underwriting issue than when the buyer goes silent past the deadline.
Waiving the Contingency in Competitive Markets and the Risk You Take
In seller's markets, buyers sometimes waive the mortgage contingency to make their offers more attractive. A seller who receives multiple bids may favor a buyer who removes the financing contingency because it reduces the chance the deal will fall apart. Waiving the clause can indeed strengthen an offer, but it transfers the financing risk entirely to the buyer: if the loan is denied, the buyer may lose the earnest money deposit, which can be thousands of dollars.
The decision to waive should never be automatic. Buyers who consider it should first confirm that they have a fully underwritten pre-approval, not just a prequalification, and that their financial profile is clean enough to survive underwriting. They should also understand the specific risks they are accepting, including the possibility of a low appraisal, a last-minute employment change, or a lender's stricter review of self-employment income.
A middle path exists in many contracts: a shortened contingency period or a partial waiver with a cap on the buyer's liability. Some buyers agree to a smaller deposit at risk, or a contingency that only covers a narrow set of financing failures. These compromises preserve some protection while signaling seriousness to the seller.
Getting pre-approved early is the single most effective way to strengthen an offer without giving up your safety net. A pre-approval letter from a lender shows the seller that your financing has already been reviewed, which can make a contingency-bearing offer nearly as competitive as a waived one. Buyers who compare lenders and secure a strong pre-approval before house hunting are in the best position to negotiate. Resources such as RefinancingCo offer educational guides and calculators that help buyers understand their borrowing power before they make an offer.
Appraisal Contingency Versus Financing Contingency
Buyers often confuse the appraisal contingency with the financing contingency, but they protect against different problems. The financing contingency addresses whether the buyer can obtain a loan at all. The appraisal contingency addresses whether the property appraises for at least the purchase price, which matters because lenders base loan amounts on the appraised value, not the contract price.
If the home appraises below the agreed price, the lender may reduce the loan amount, leaving the buyer to cover the gap in cash. An appraisal contingency gives the buyer the right to renegotiate, walk away, or proceed depending on the contract terms. Some purchase agreements combine both protections into a single financing clause, while others treat them as separate provisions with separate deadlines.
Understanding both clauses helps you see the full picture of your risk. A buyer with a financing contingency but no appraisal contingency could still be forced to bring extra cash to closing if the appraisal comes in low. A buyer with both contingencies has broader protection, though sellers may view the offer as slightly less firm. The right balance depends on your market, your cash reserves, and how competitive your offer needs to be.
How Pre-Approval Strengthens Your Offer and Protects Your Deposit
Pre-approval is the foundation of a strong offer and a smooth contingency period. Unlike prequalification, which is a quick estimate, pre-approval involves a lender reviewing your income, assets, credit, and debts and issuing a conditional commitment. Sellers and their agents treat pre-approved buyers as lower-risk, which can make your offer more attractive even when it includes a financing contingency.
Pre-approval also shortens the contingency period because much of the underwriting work is already done. A buyer who has been pre-approved can often move from contract to clear-to-close faster, reducing the time the seller must wait. That speed is valuable in competitive markets and can be a negotiating point when sellers push for shorter timelines.
Finally, pre-approval helps you set a realistic budget before you fall in love with a home. Knowing your maximum loan amount and comfortable monthly payment prevents the disappointment of a failed contingency later. MortgageZone's mortgage calculator and lender comparison tools can help you estimate payments and connect with participating lenders who can issue a pre-approval tailored to your situation.
A mortgage contingency is more than a legal formality. It is the clause that lets you pursue homeownership with confidence, knowing your deposit is protected if financing does not come through. Read it carefully, understand its deadlines, and pair it with a strong pre-approval so your offer stands out for all the right reasons.